The BharatPe Business Model of Merchant QR Codes and Loans
How BharatPe earns from shop payments, devices and merchant loans.

Key Takeaways
- FY25 revenue from operations rose to ₹1,667 crore from ₹1,426 crore.
- FY25 net loss narrowed to ₹88.2 crore from ₹492 crore in FY24.
- About 60% of FY25 revenue came from financial services, mainly lending.
- BharatPe says it serves 1.7 crore merchants in over 450 cities in India.
Table of Contents 12 sections
- BharatPe at a glance
- What is BharatPe
- How does BharatPe make money
- How BharatPe revenue has changed since FY22
- BharatPe Business Model Canvas
- BharatPe revenue and loss over the years
- BharatPe and its NBFC
- BharatPe journey so far
- Who BharatPe competes with
- Challenges BharatPe faces
- Conclusion on the BharatPe business model
- FAQs
The BharatPe business model gives small shopkeepers QR codes to accept UPI payments, then earns from card machines, payment services and loans to the same merchants. Its lending runs through its own NBFC, BharatPe Capital, and through partner lenders.
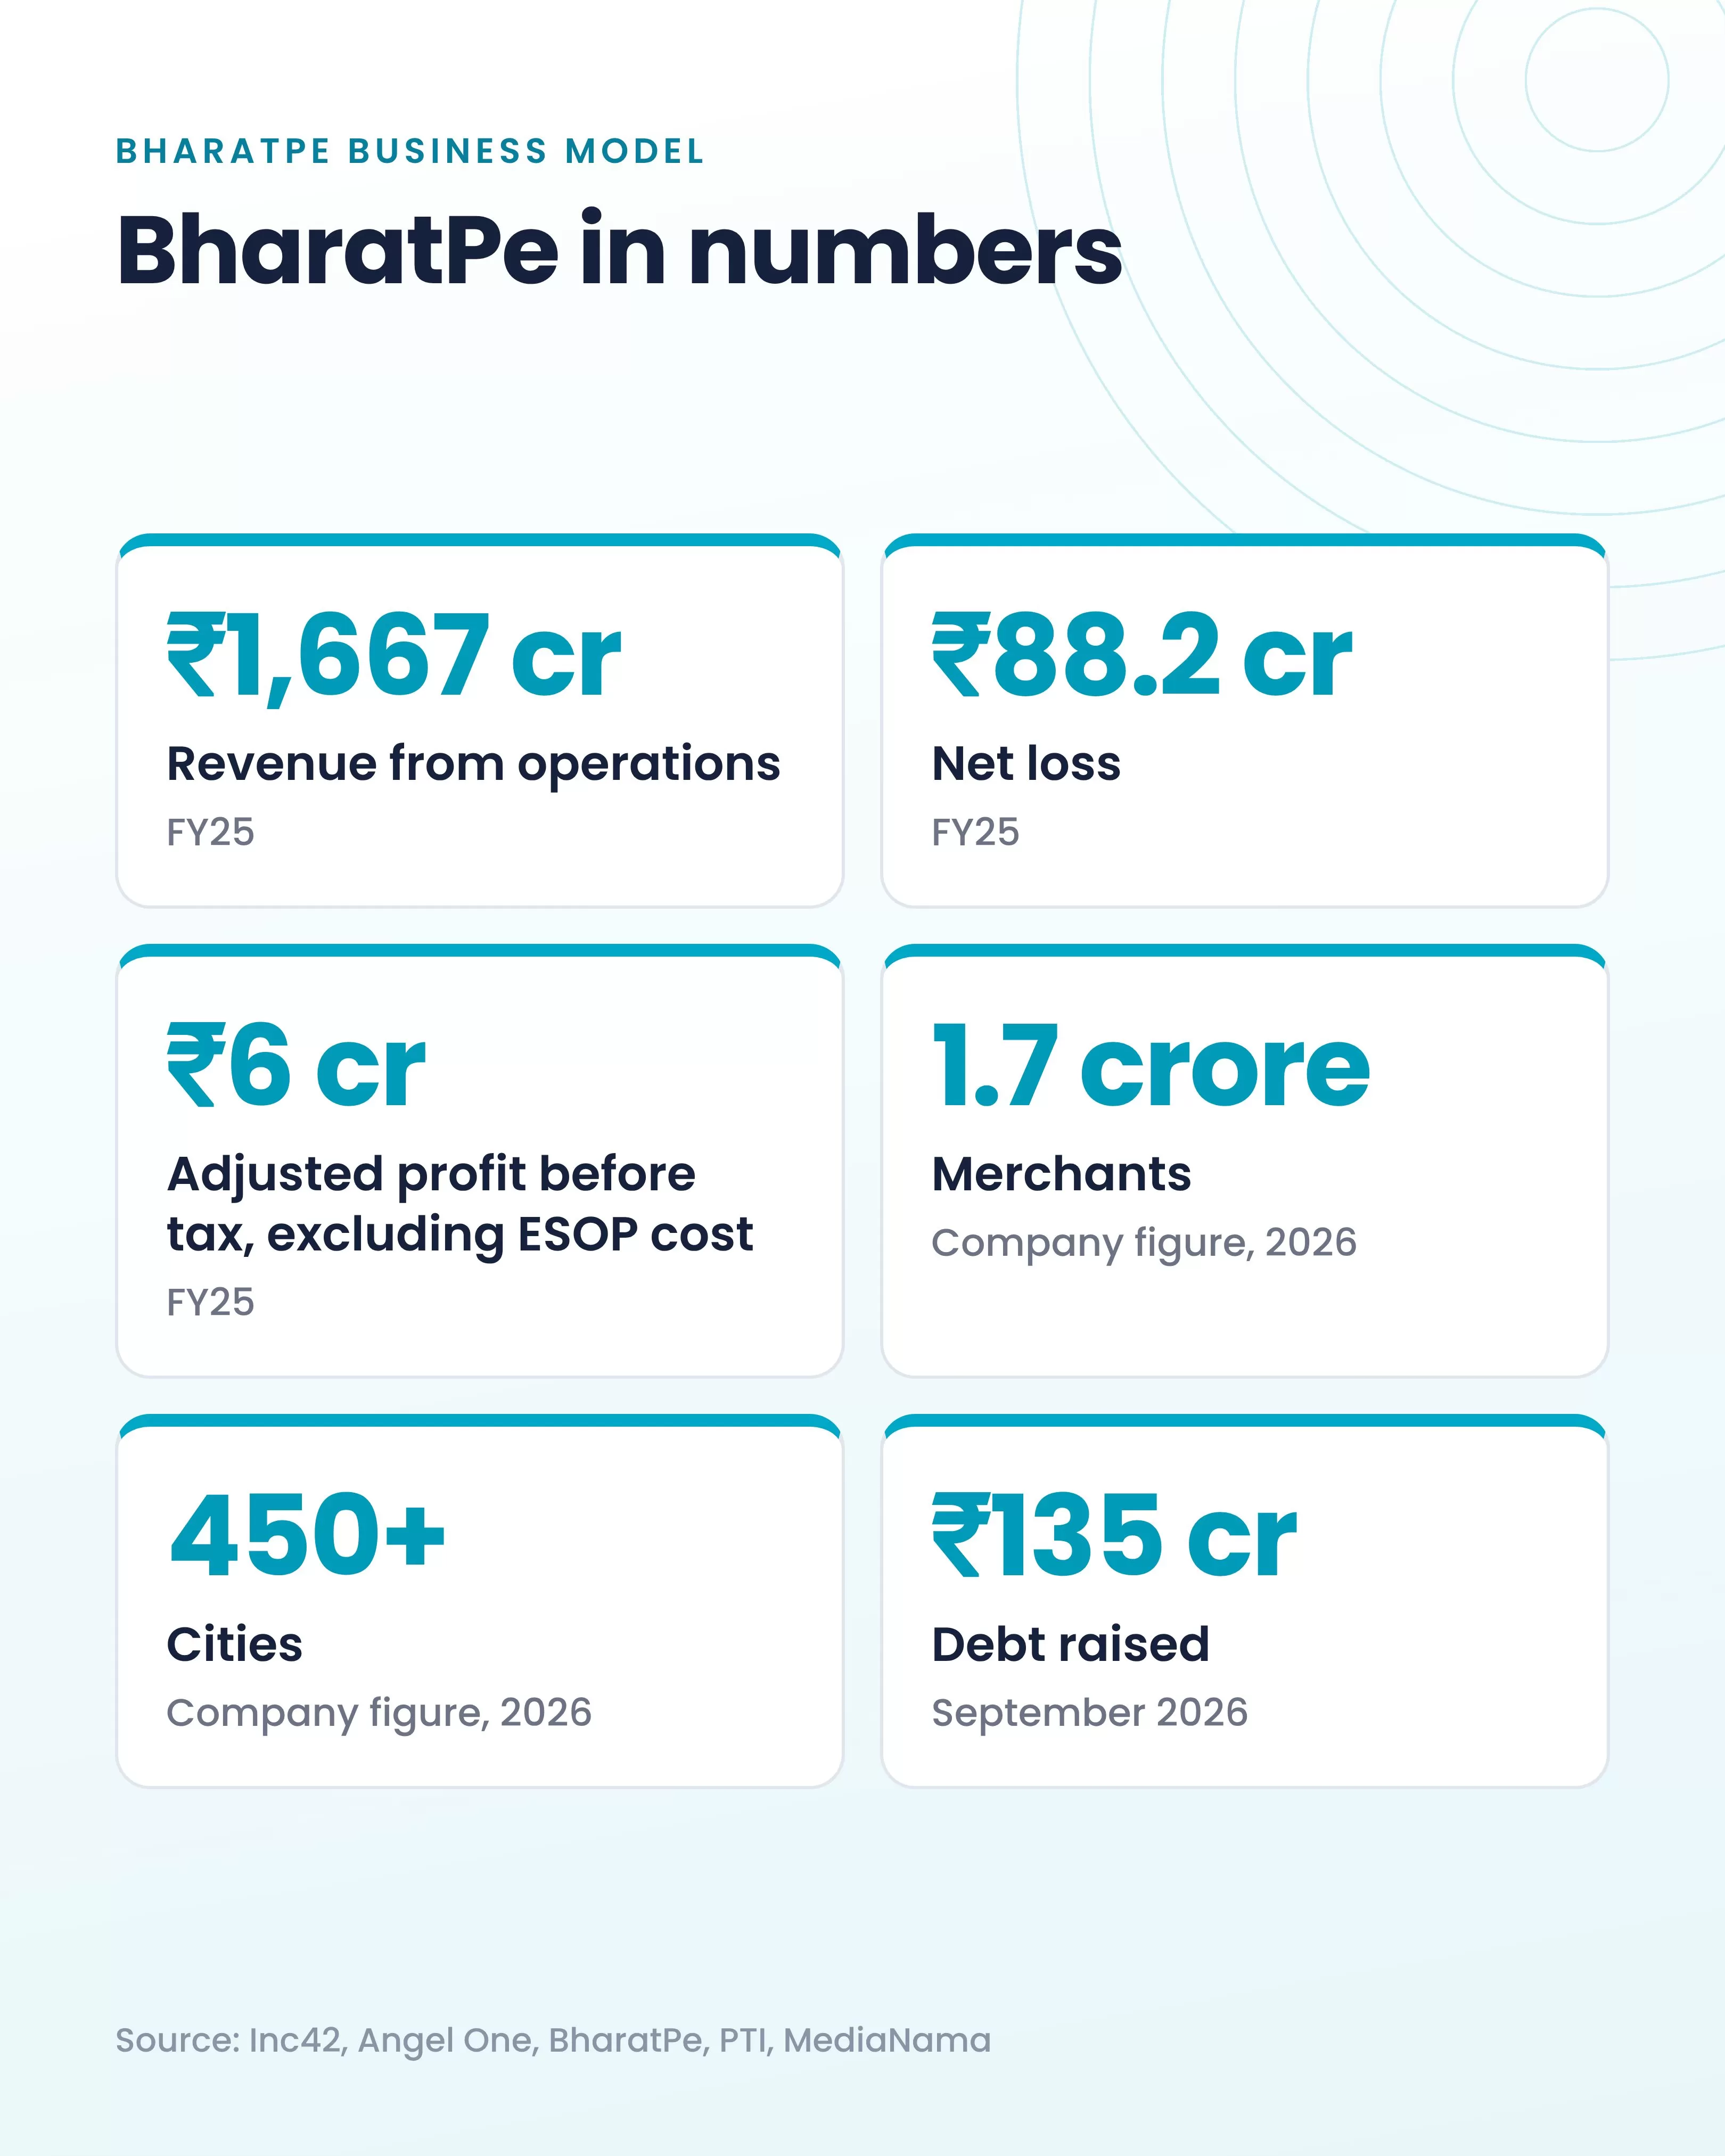
In FY25, BharatPe reported revenue from operations of ₹1,667 crore and a net loss of ₹88.2 crore. On an adjusted basis that excludes ESOP costs, it reported a profit before tax of ₹6 crore.
BharatPe at a glance
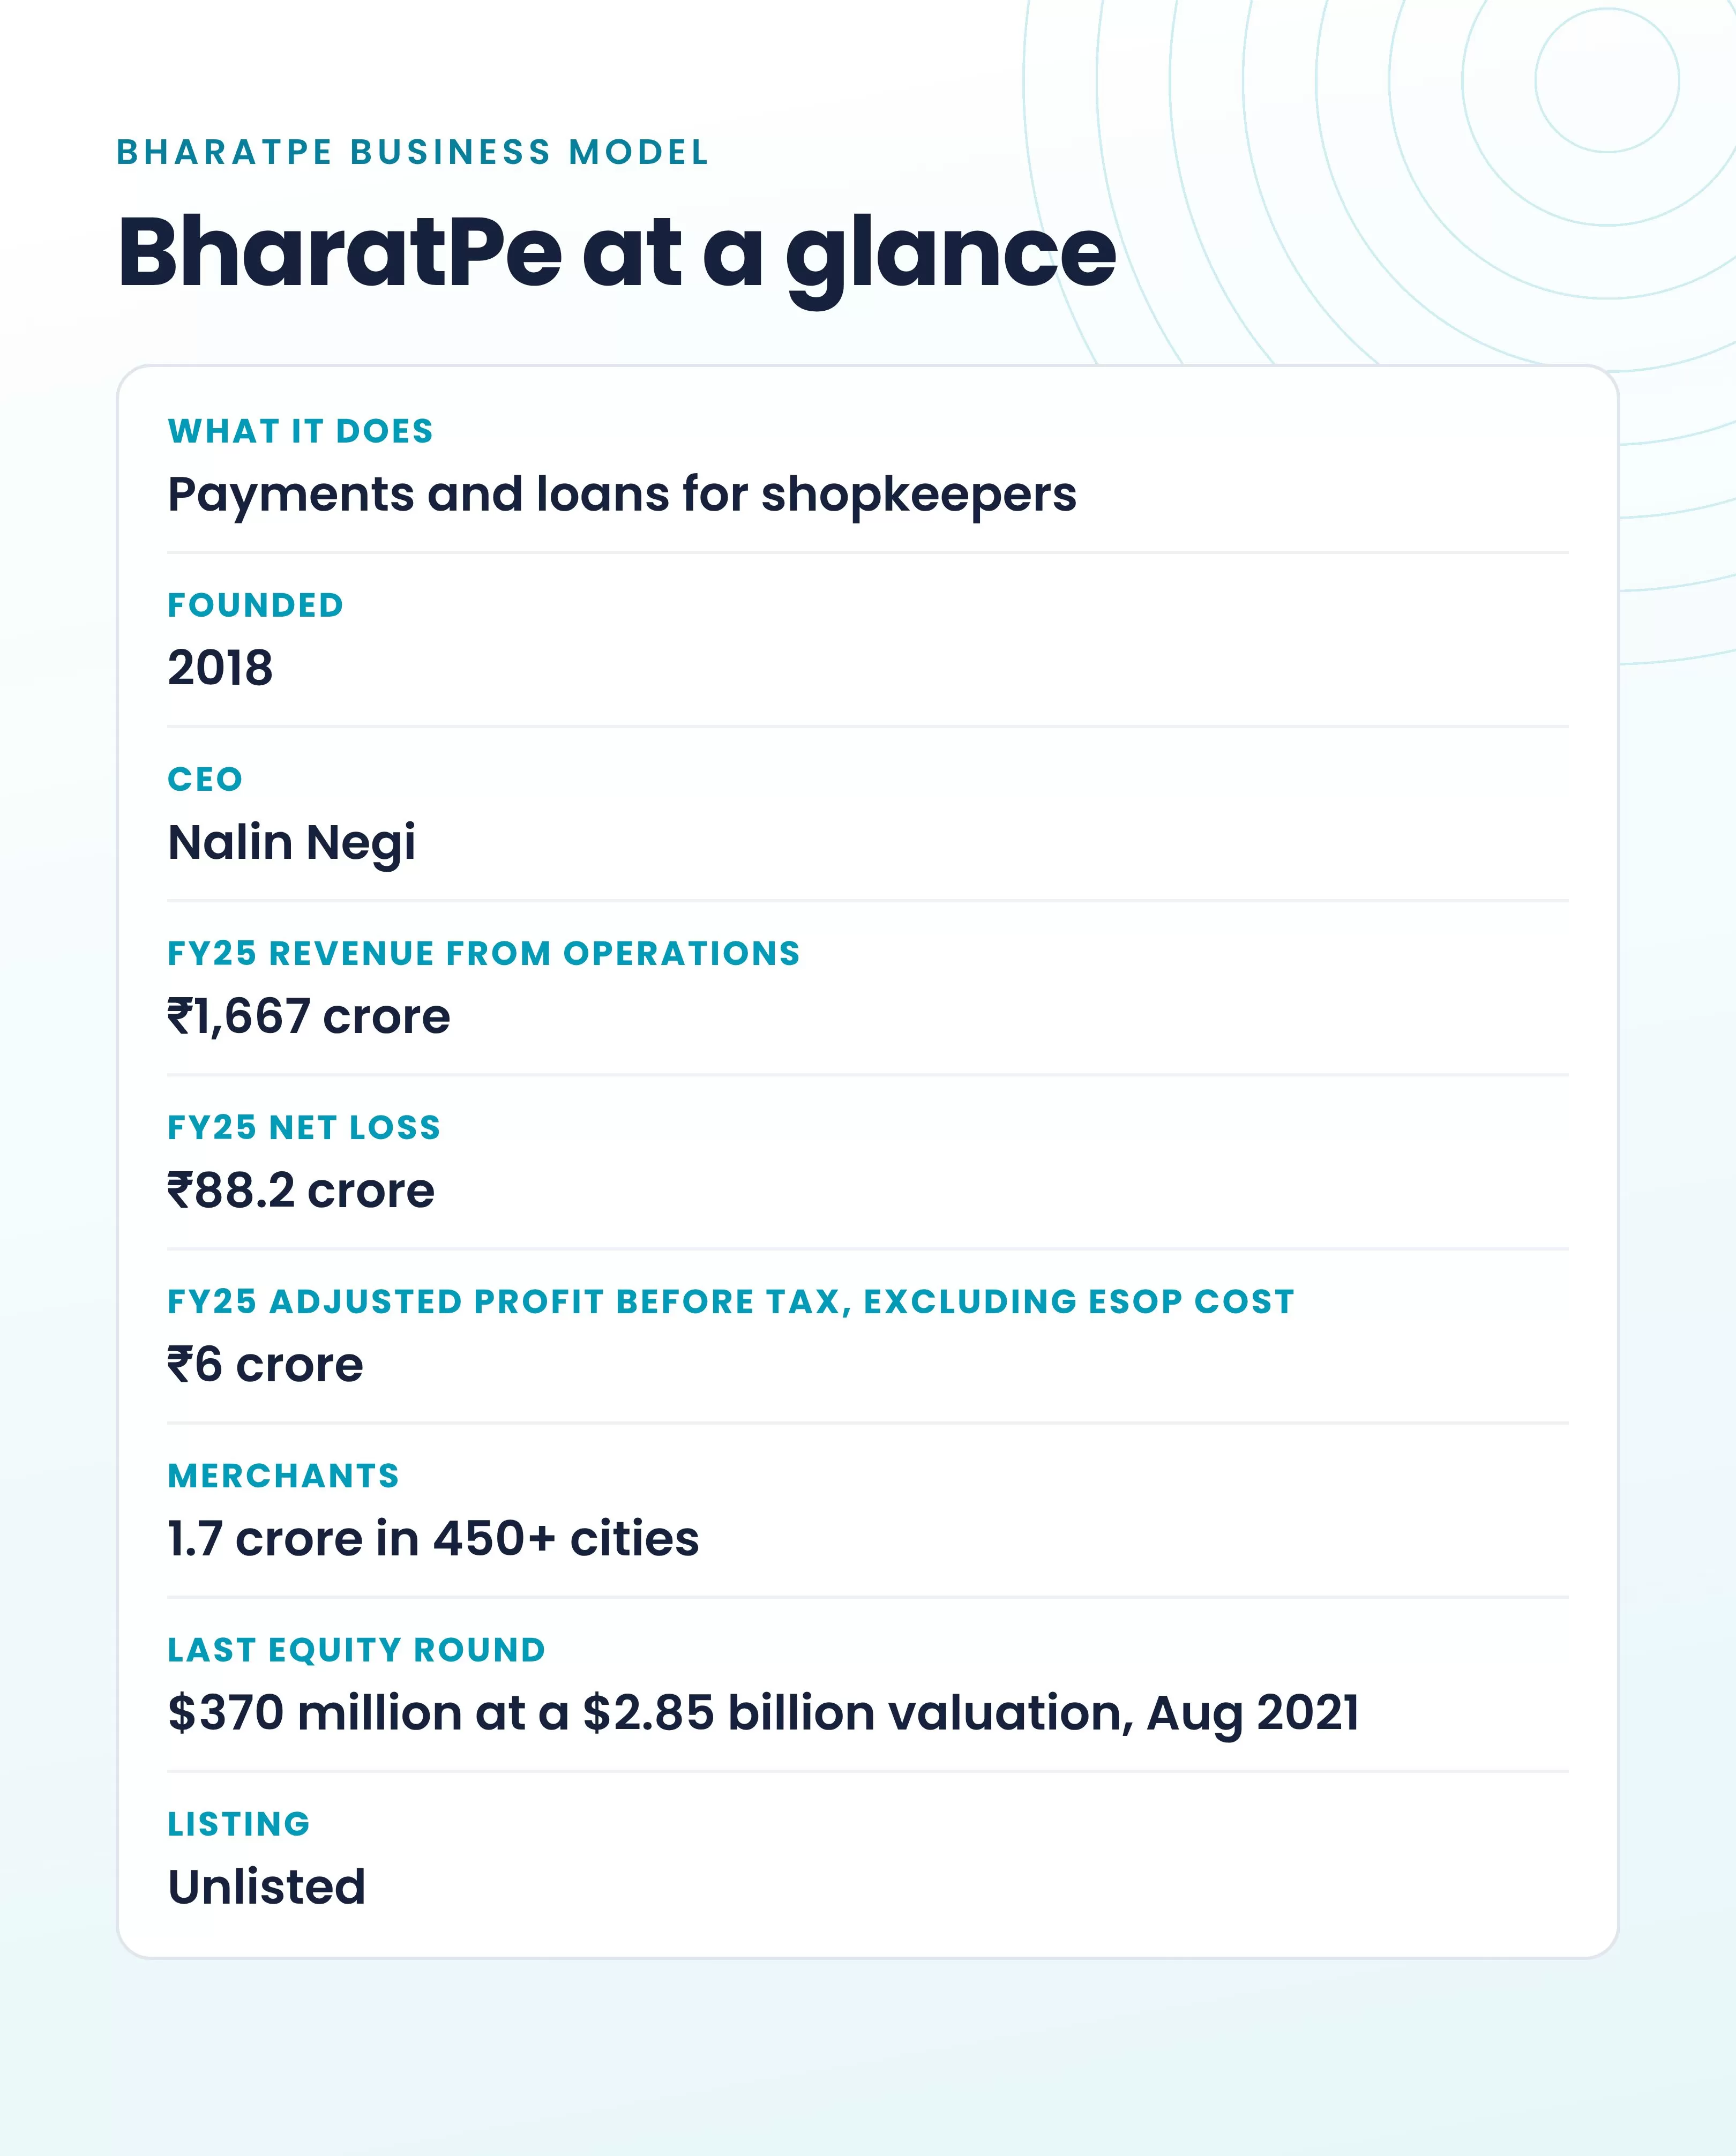
| Item | Detail |
|---|---|
| What it does | Payments and loans for shopkeepers |
| Founded | 2018 |
| CEO | Nalin Negi |
| FY25 revenue from operations | ₹1,667 crore |
| FY25 net loss | ₹88.2 crore |
| FY25 adjusted profit before tax, excluding ESOP cost | ₹6 crore |
| Merchants | 1.7 crore in over 450 cities (company figure) |
| Last equity round | $370 million Series E at a $2.85 billion valuation, August 2021 |
| Listing | Unlisted |
What is BharatPe
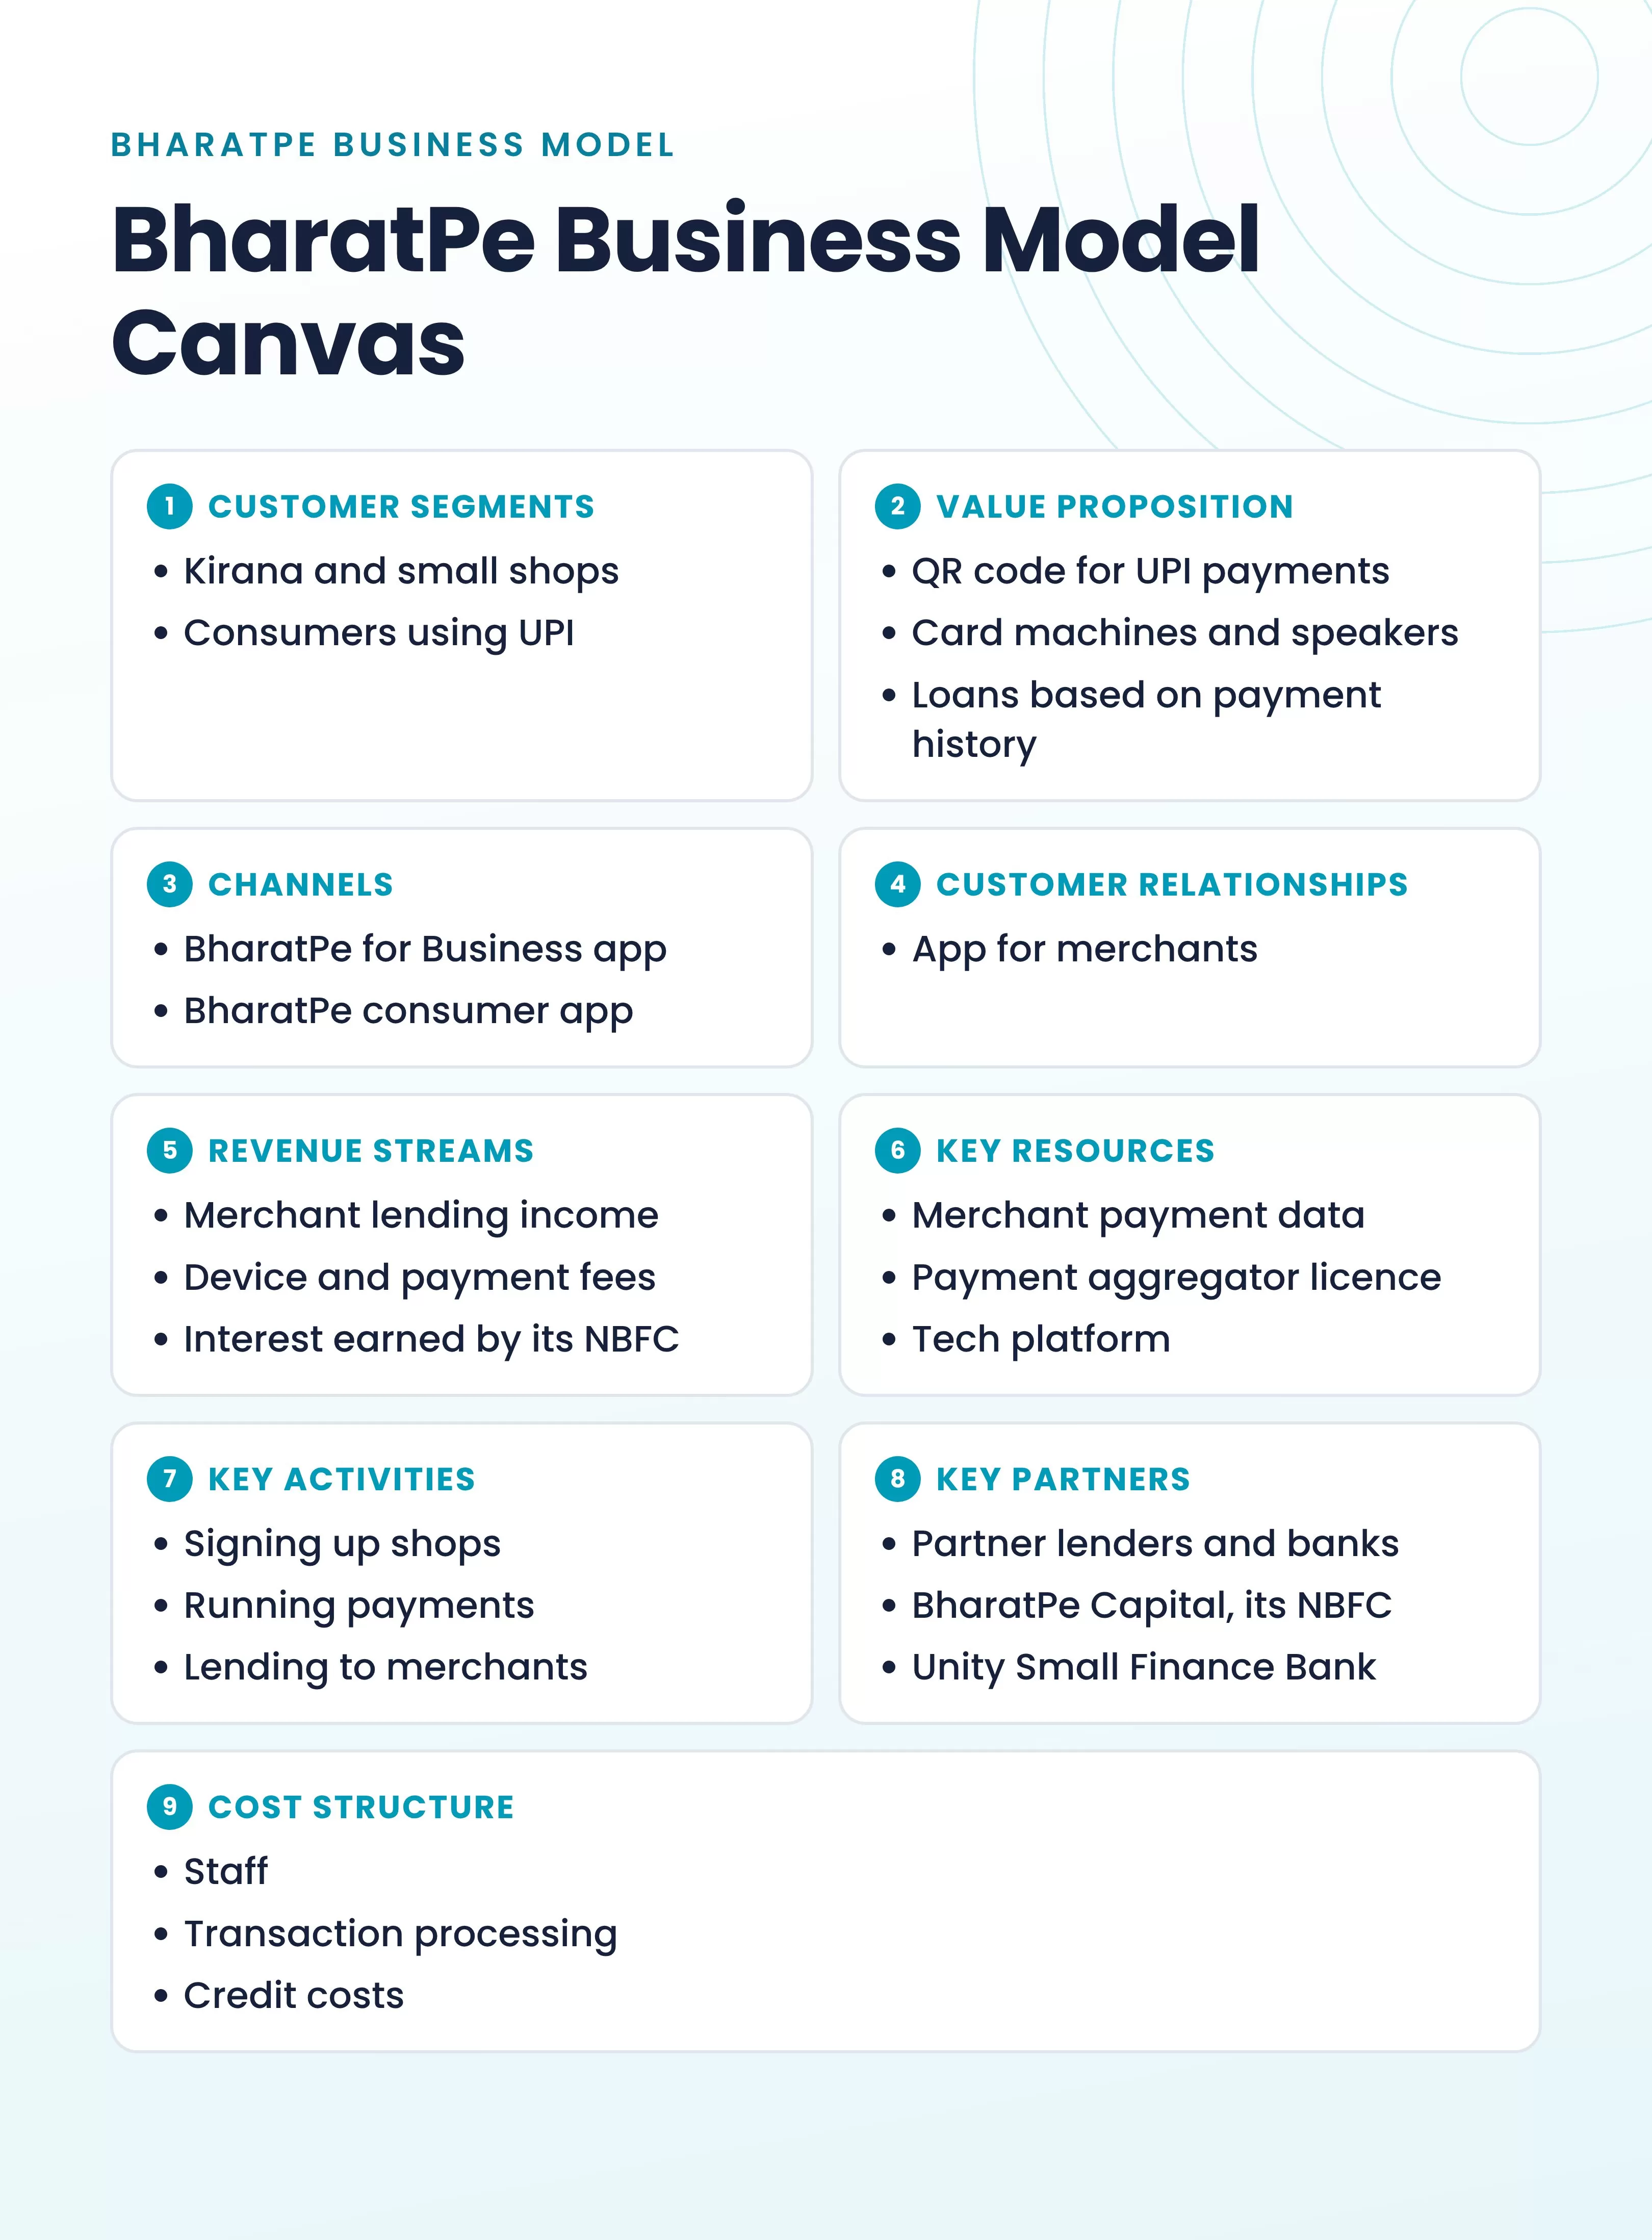
BharatPe is a fintech company built for kirana stores and other small shops. A shop gets a BharatPe QR code that accepts UPI payments from any UPI app. BharatPe also offers card machines under the BharatPe Swipe name, an all-in-one payment device called BharatPe One, and a payment speaker that reads out each payment received.
On top of payments, the company sells financial products. Merchants can take business loans, and consumers can use the BharatPe app for UPI payments, bill payments and investments. BharatPe Flex, launched with YES BANK, brings credit on UPI to eligible consumers. BharatPe says it serves 1.7 crore merchants in over 450 cities.
How does BharatPe make money
BharatPe earns from two broad lines: payments and financial services. Payments covers device subscriptions, QR codes and UPI. Financial services is mainly lending to merchants.
BharatPe revenue model by stream
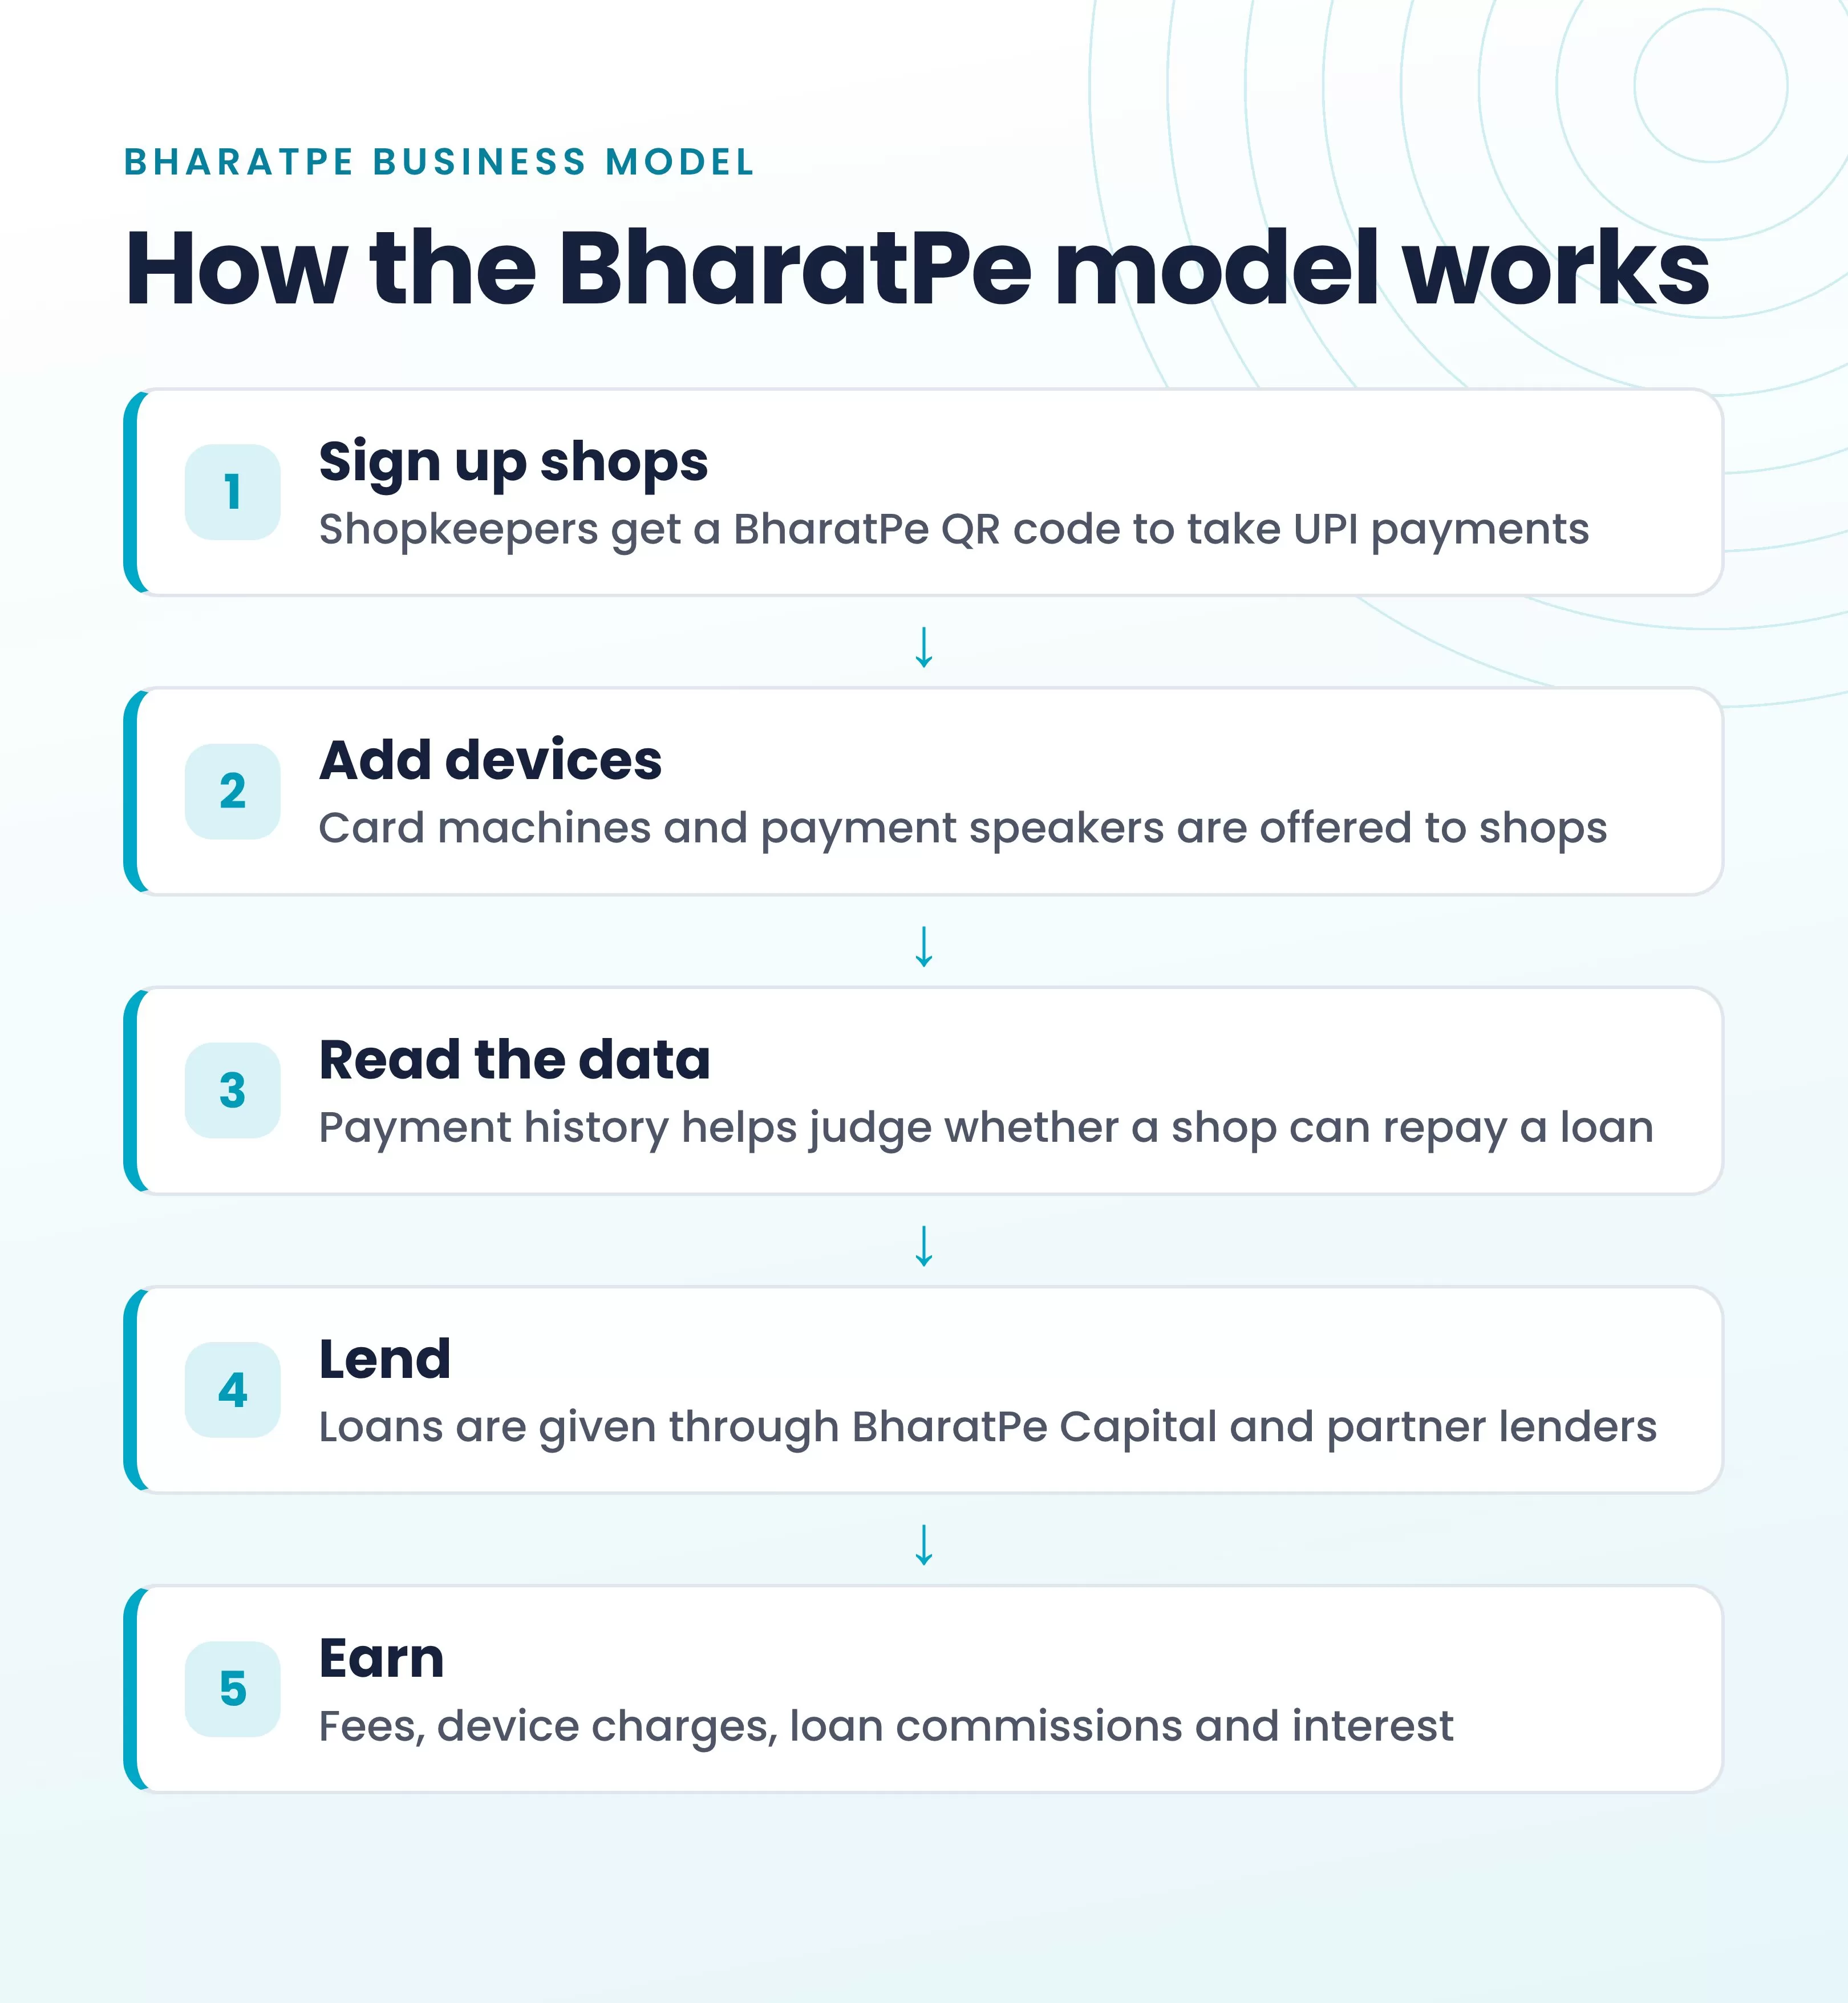
- Merchant lending. BharatPe uses a shop's payment history to judge whether it can repay a loan. Loans come from its own NBFC, BharatPe Capital, and from partner lenders.
- Devices and payment services. Card machines, the all-in-one BharatPe One device and payment speakers are offered to merchants. Its subsidiary also runs an online payment gateway under the BharatPe X name.
- Consumer products. The BharatPe app offers UPI payments, bill payments, credit on UPI and investment products.
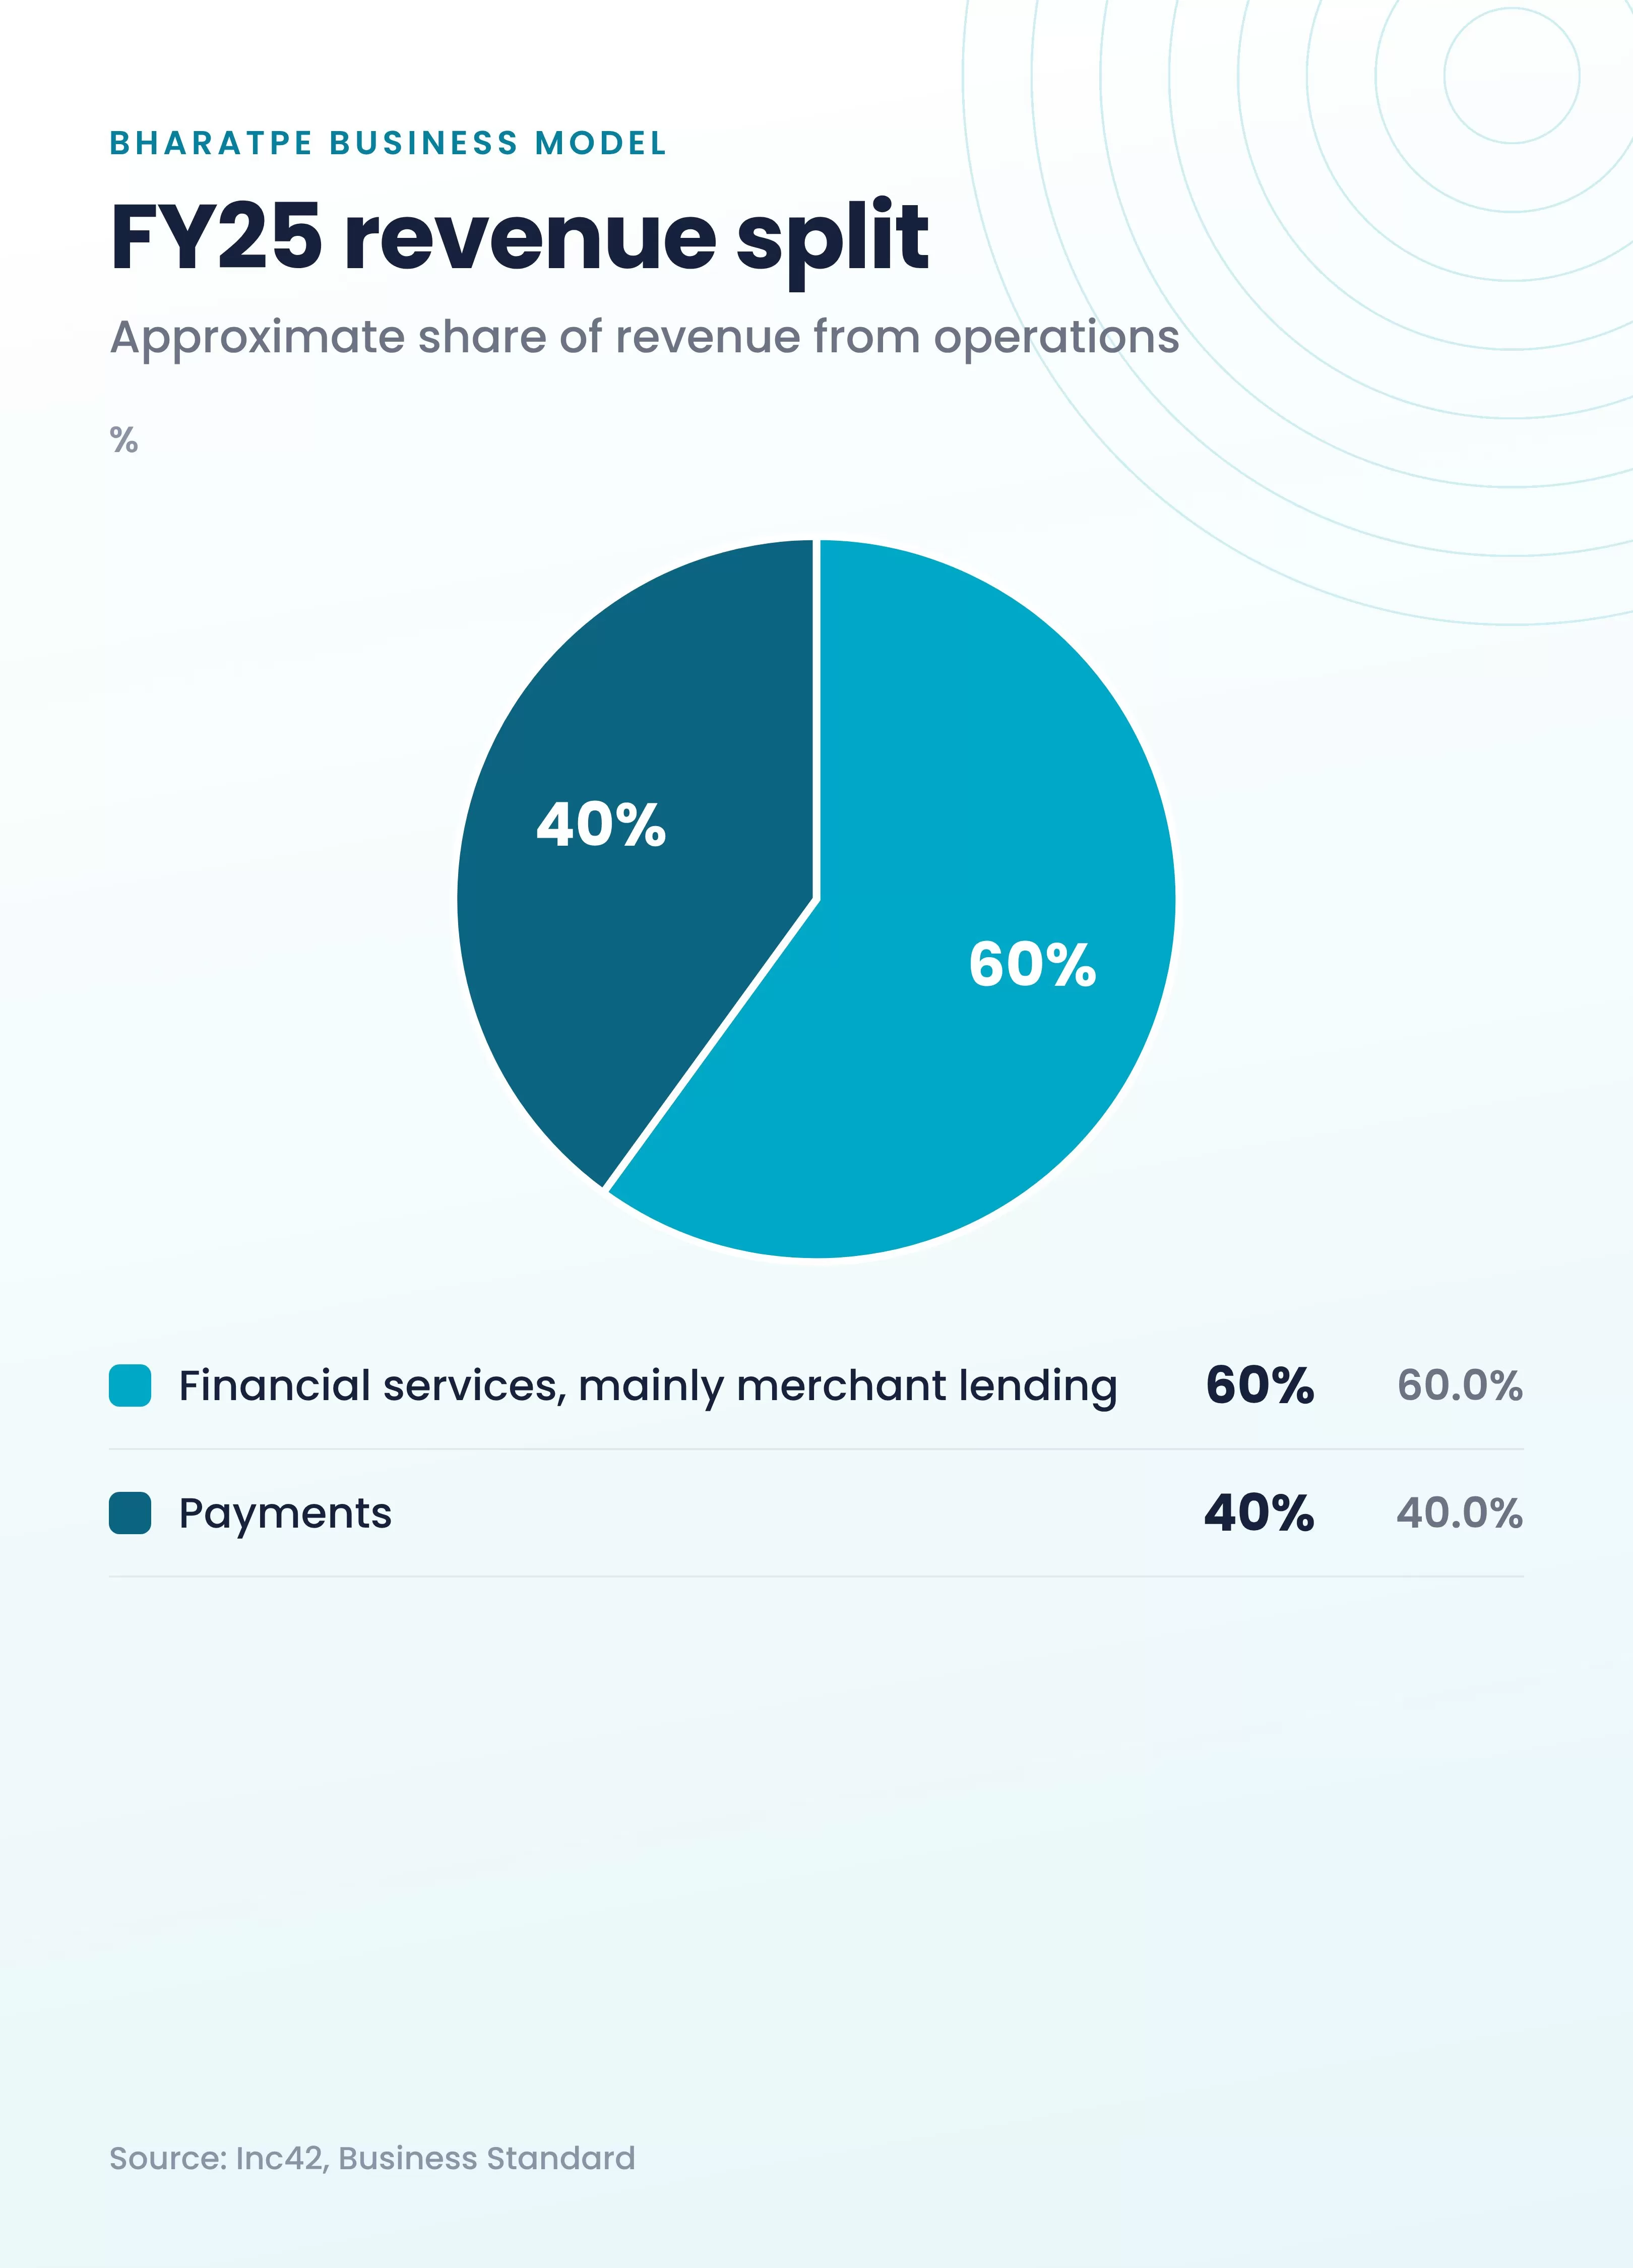
In FY25, financial services, mainly merchant lending, made up about 60% of revenue, and payments the rest.
How BharatPe lends to shops
A shop that takes payments through BharatPe builds up a record of how much money comes in each day. BharatPe uses its merchants' payment data in the same way to decide who can get a loan and how much.
The money for these loans comes from two places. Part is lent by BharatPe Capital, the NBFC in which BharatPe holds a majority stake, and part by partner lenders.
How the payments side earns
BharatPe gives shops a QR code to accept UPI payments. Card machines and payment speakers are offered to merchants who want them, and these devices are part of the payments revenue. The online payment gateway, BharatPe X, lets businesses accept payments on websites and apps.
How BharatPe revenue has changed since FY22
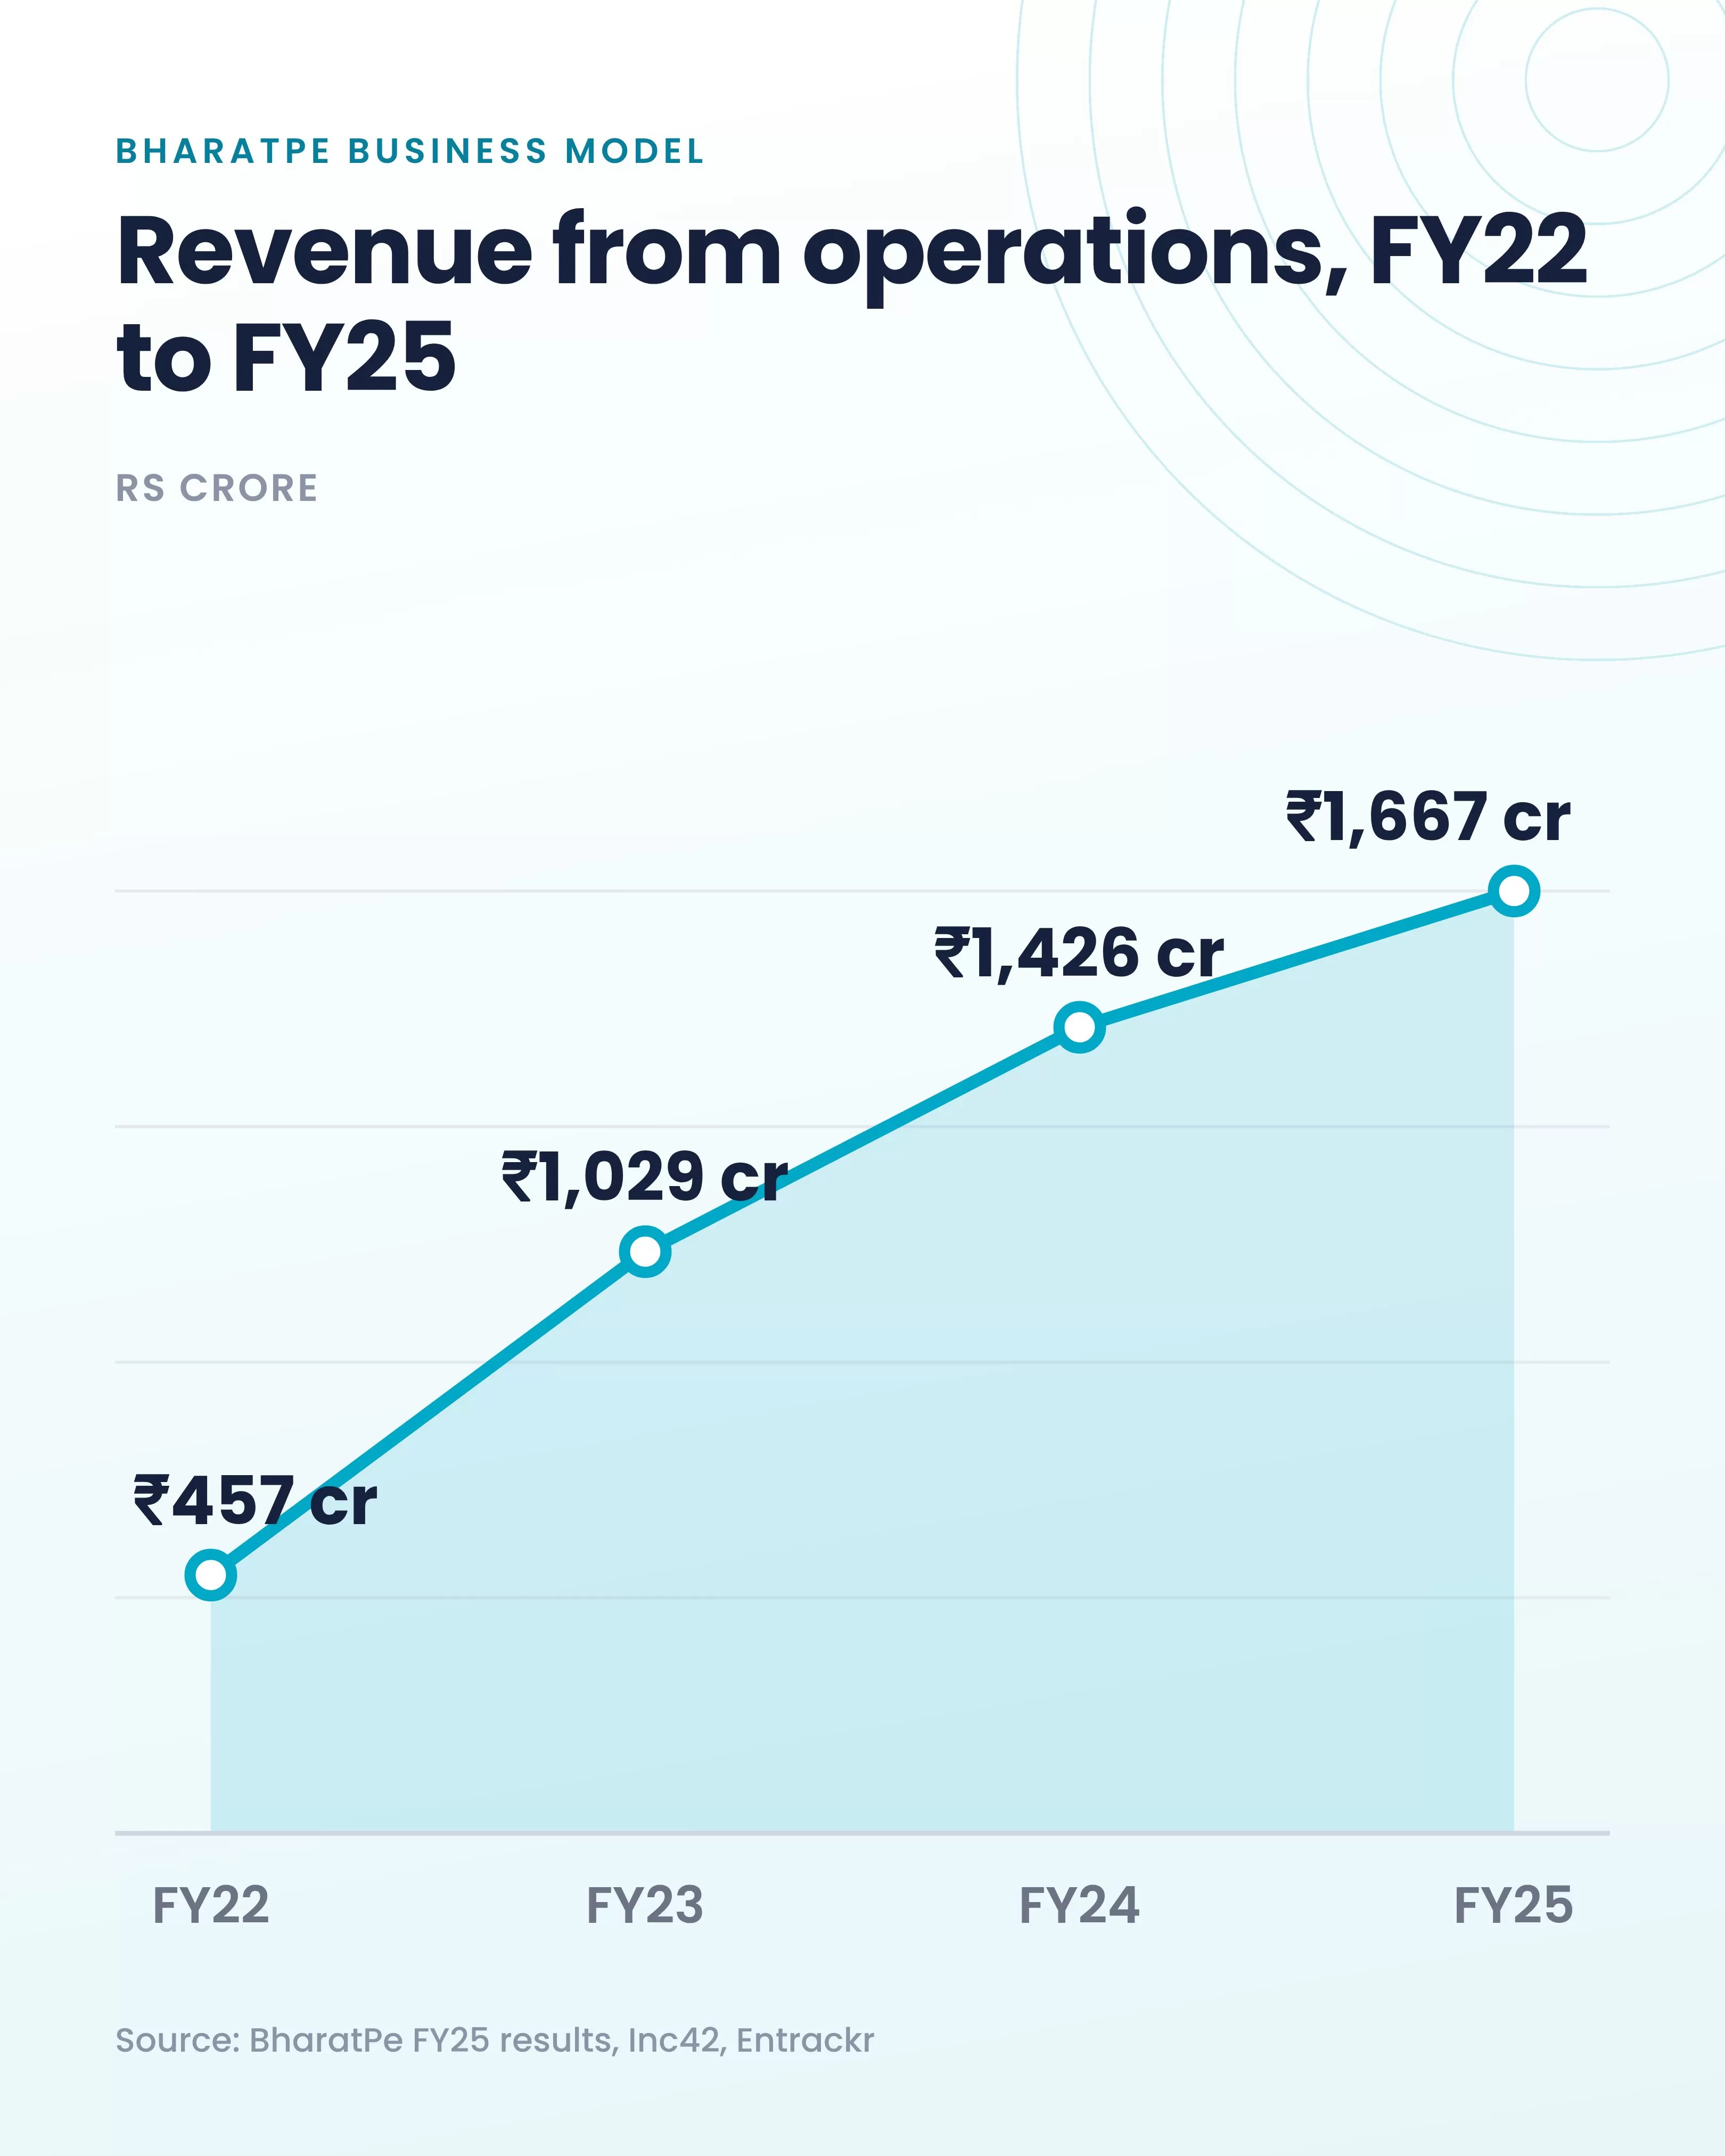
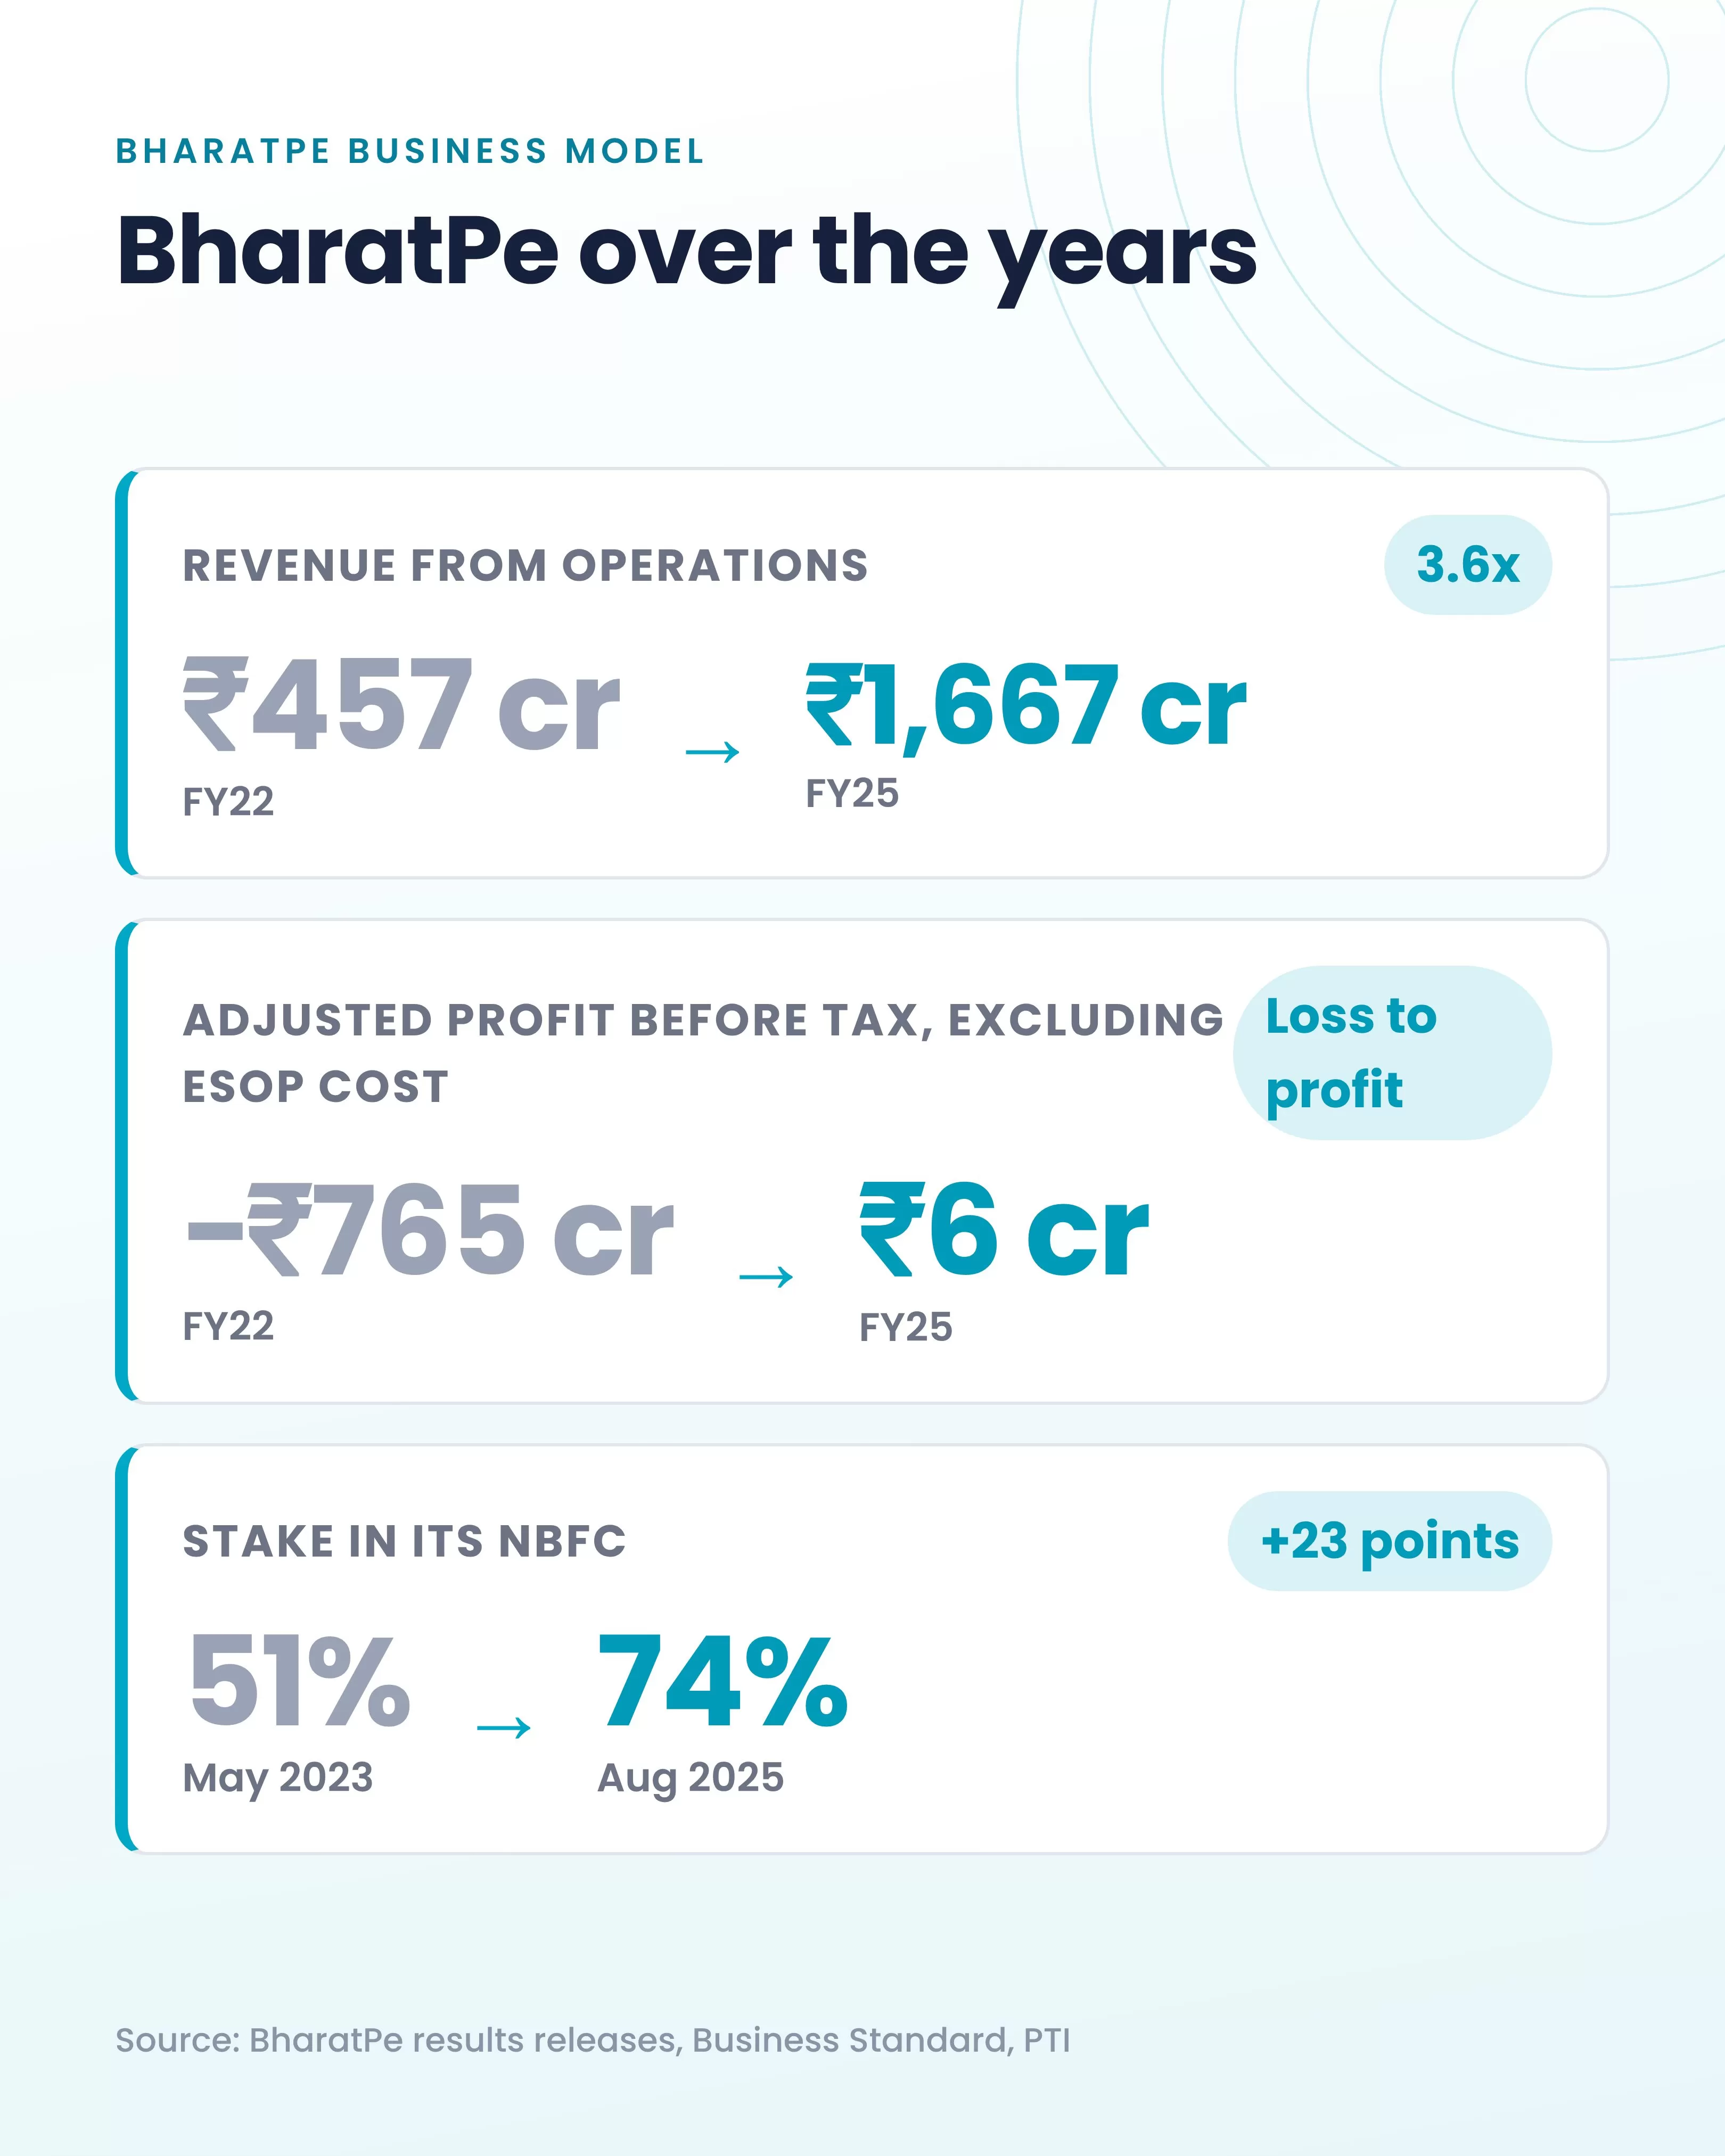
Revenue from operations rose from ₹457 crore in FY22 to ₹1,029 crore in FY23, ₹1,426 crore in FY24 and ₹1,667 crore in FY25. That is a compound annual growth rate of 54% over the three years.
BharatPe Business Model Canvas
BharatPe revenue and loss over the years
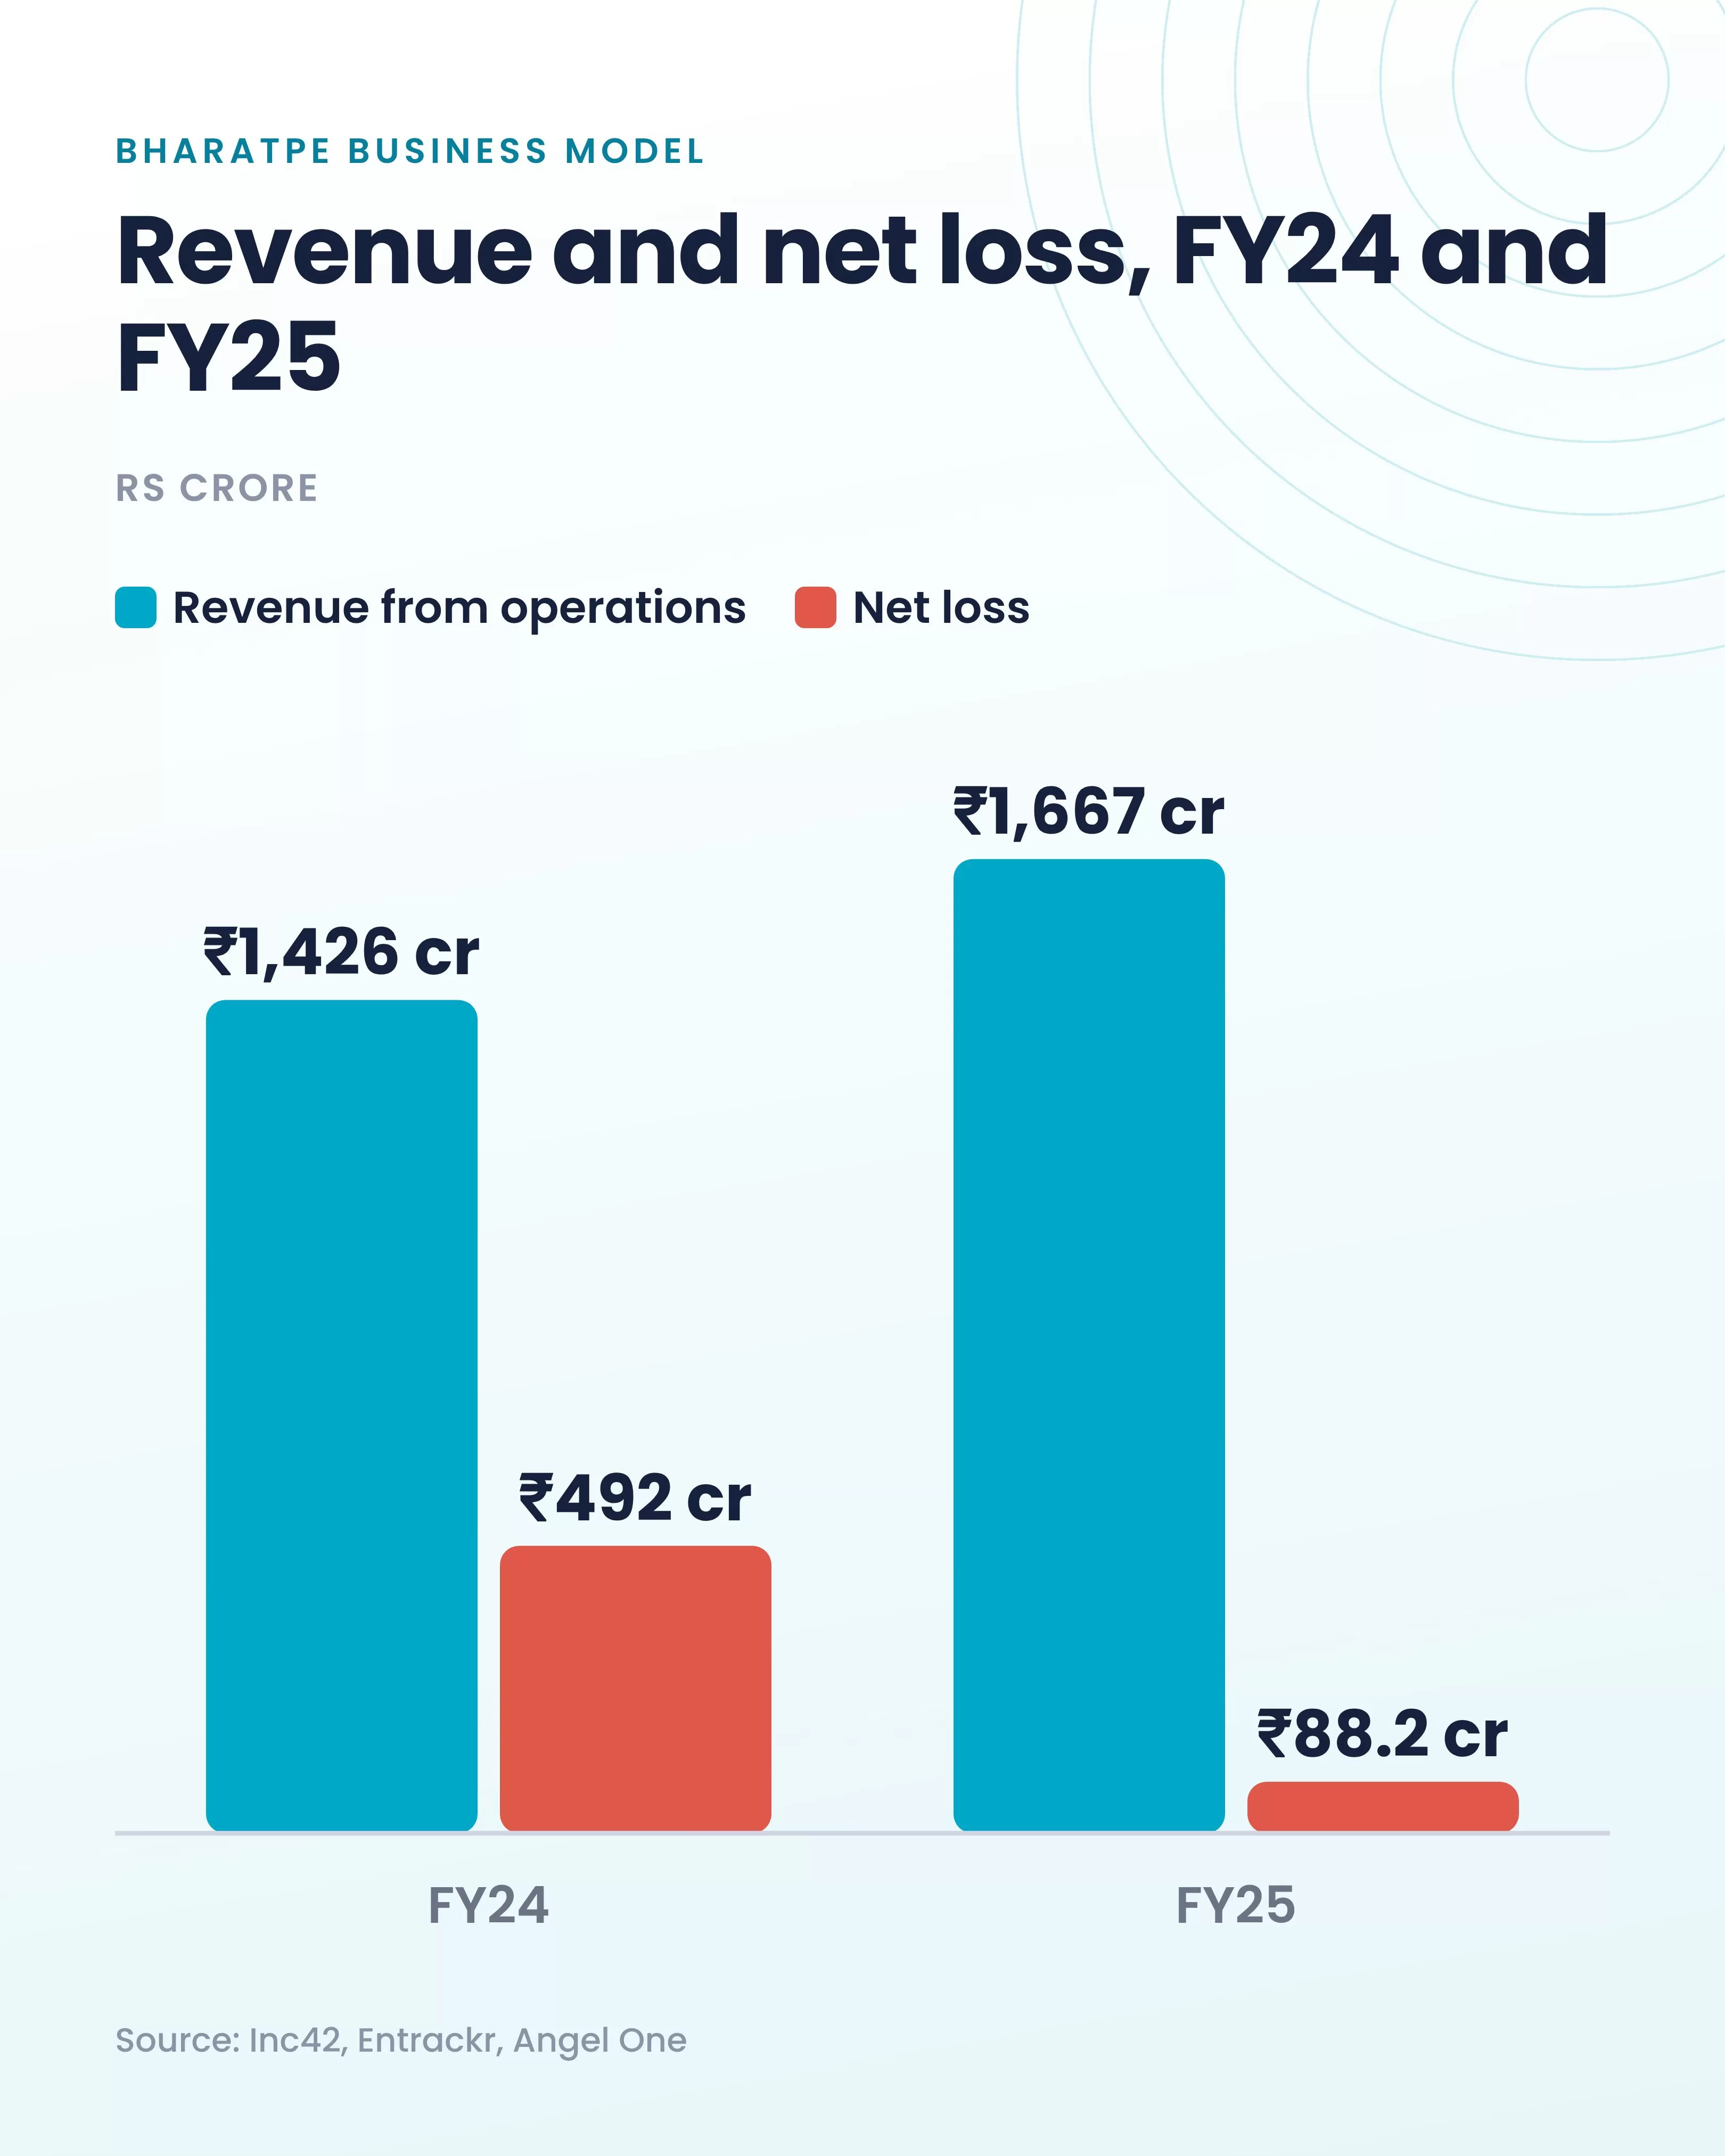
BharatPe's net loss fell from ₹492 crore in FY24 to ₹88.2 crore in FY25, while revenue from operations rose from ₹1,426 crore to ₹1,667 crore. The adjusted profit before tax, excluding ESOP costs, moved from a loss of ₹342 crore in FY24 to a profit in FY25.
In September 2026, BharatPe raised ₹135 crore in debt through non-convertible debentures, from InnoVen Capital, Neo Group and Alteria Capital.
BharatPe and its NBFC
BharatPe bought a 51% stake in the NBFC Trillion Loans in May 2023. It raised that stake to 74% by August 2025. In July 2026, Trillionloans was renamed BharatPe Capital.
BharatPe journey so far
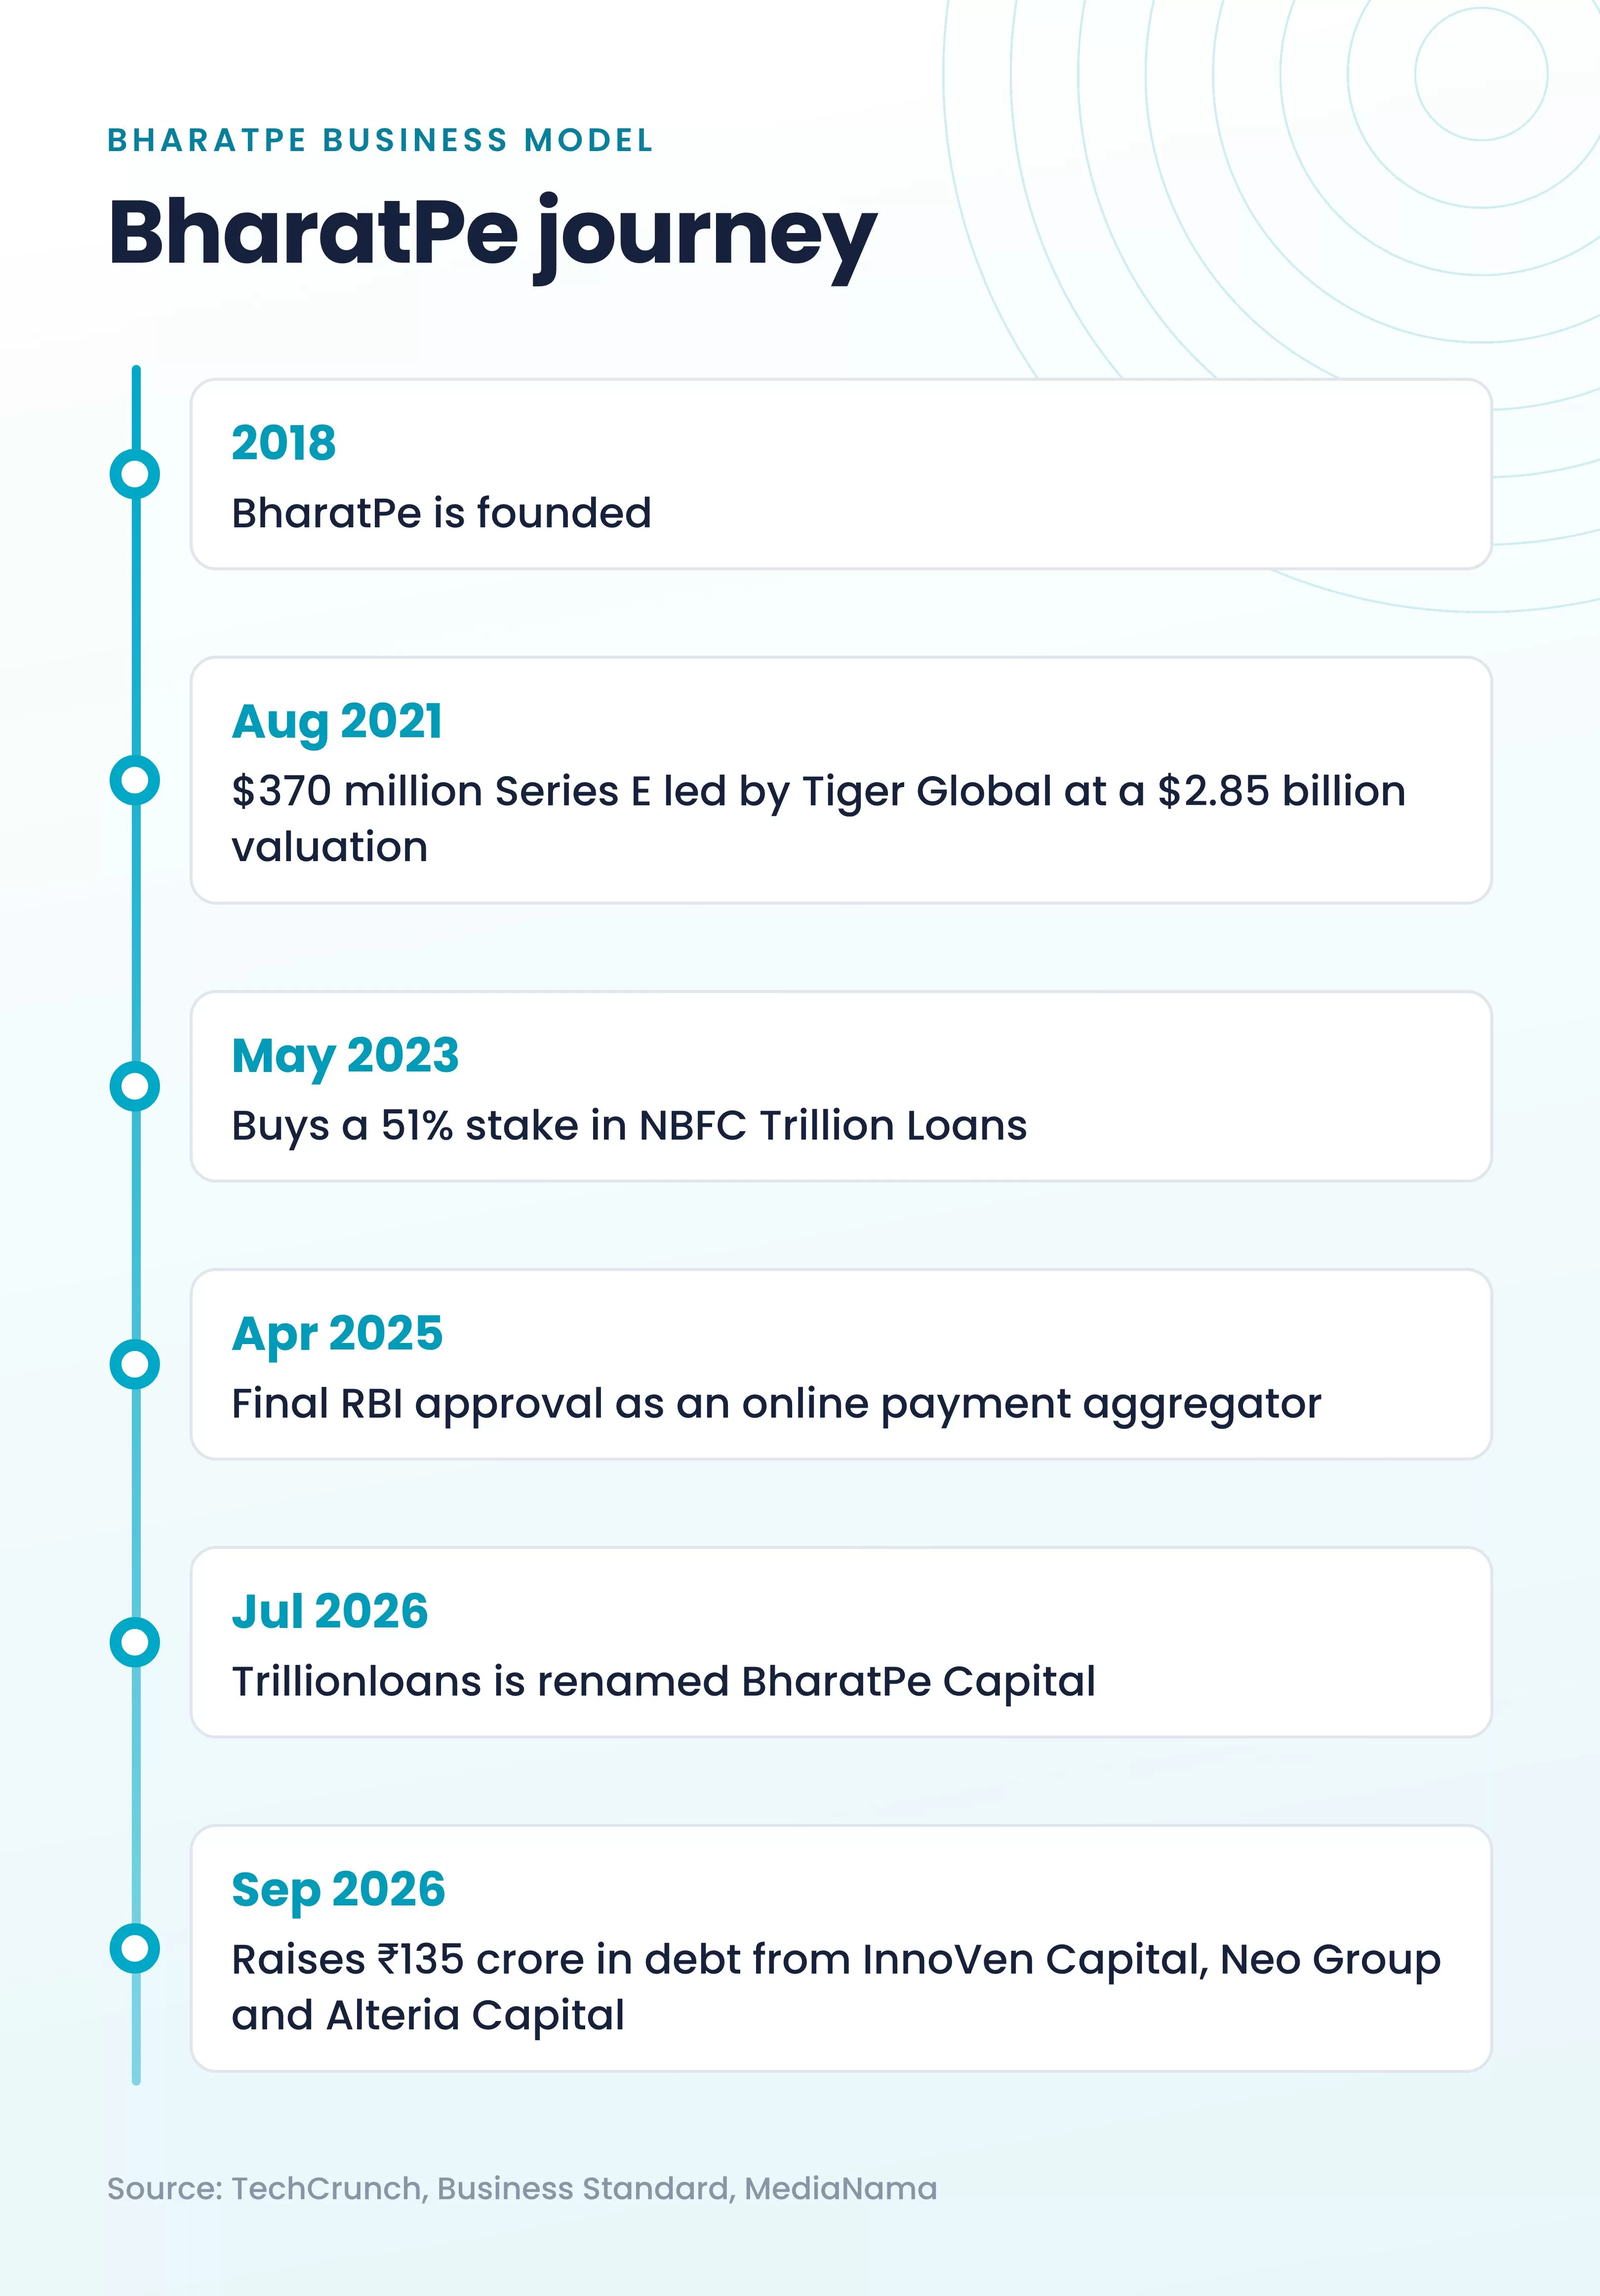
| When | What happened |
|---|---|
| 2018 | BharatPe is founded; its co-founders include Shashvat Nakrani and Ashneer Grover |
| August 2021 | Raises a $370 million Series E led by Tiger Global at a $2.85 billion valuation |
| November 2021 | Unity Small Finance Bank, a venture of Centrum and BharatPe, begins operations |
| May 2023 | Buys a 51% stake in the NBFC Trillion Loans |
| September 2024 | Settles its dispute with Ashneer Grover, who no longer holds shares or any role |
| April 2025 | Its arm Resilient Payments gets final RBI approval as an online payment aggregator |
| July 2026 | Trillionloans is renamed BharatPe Capital |
| September 2026 | Raises ₹135 crore in debt from InnoVen Capital, Neo Group and Alteria Capital |
Who BharatPe competes with
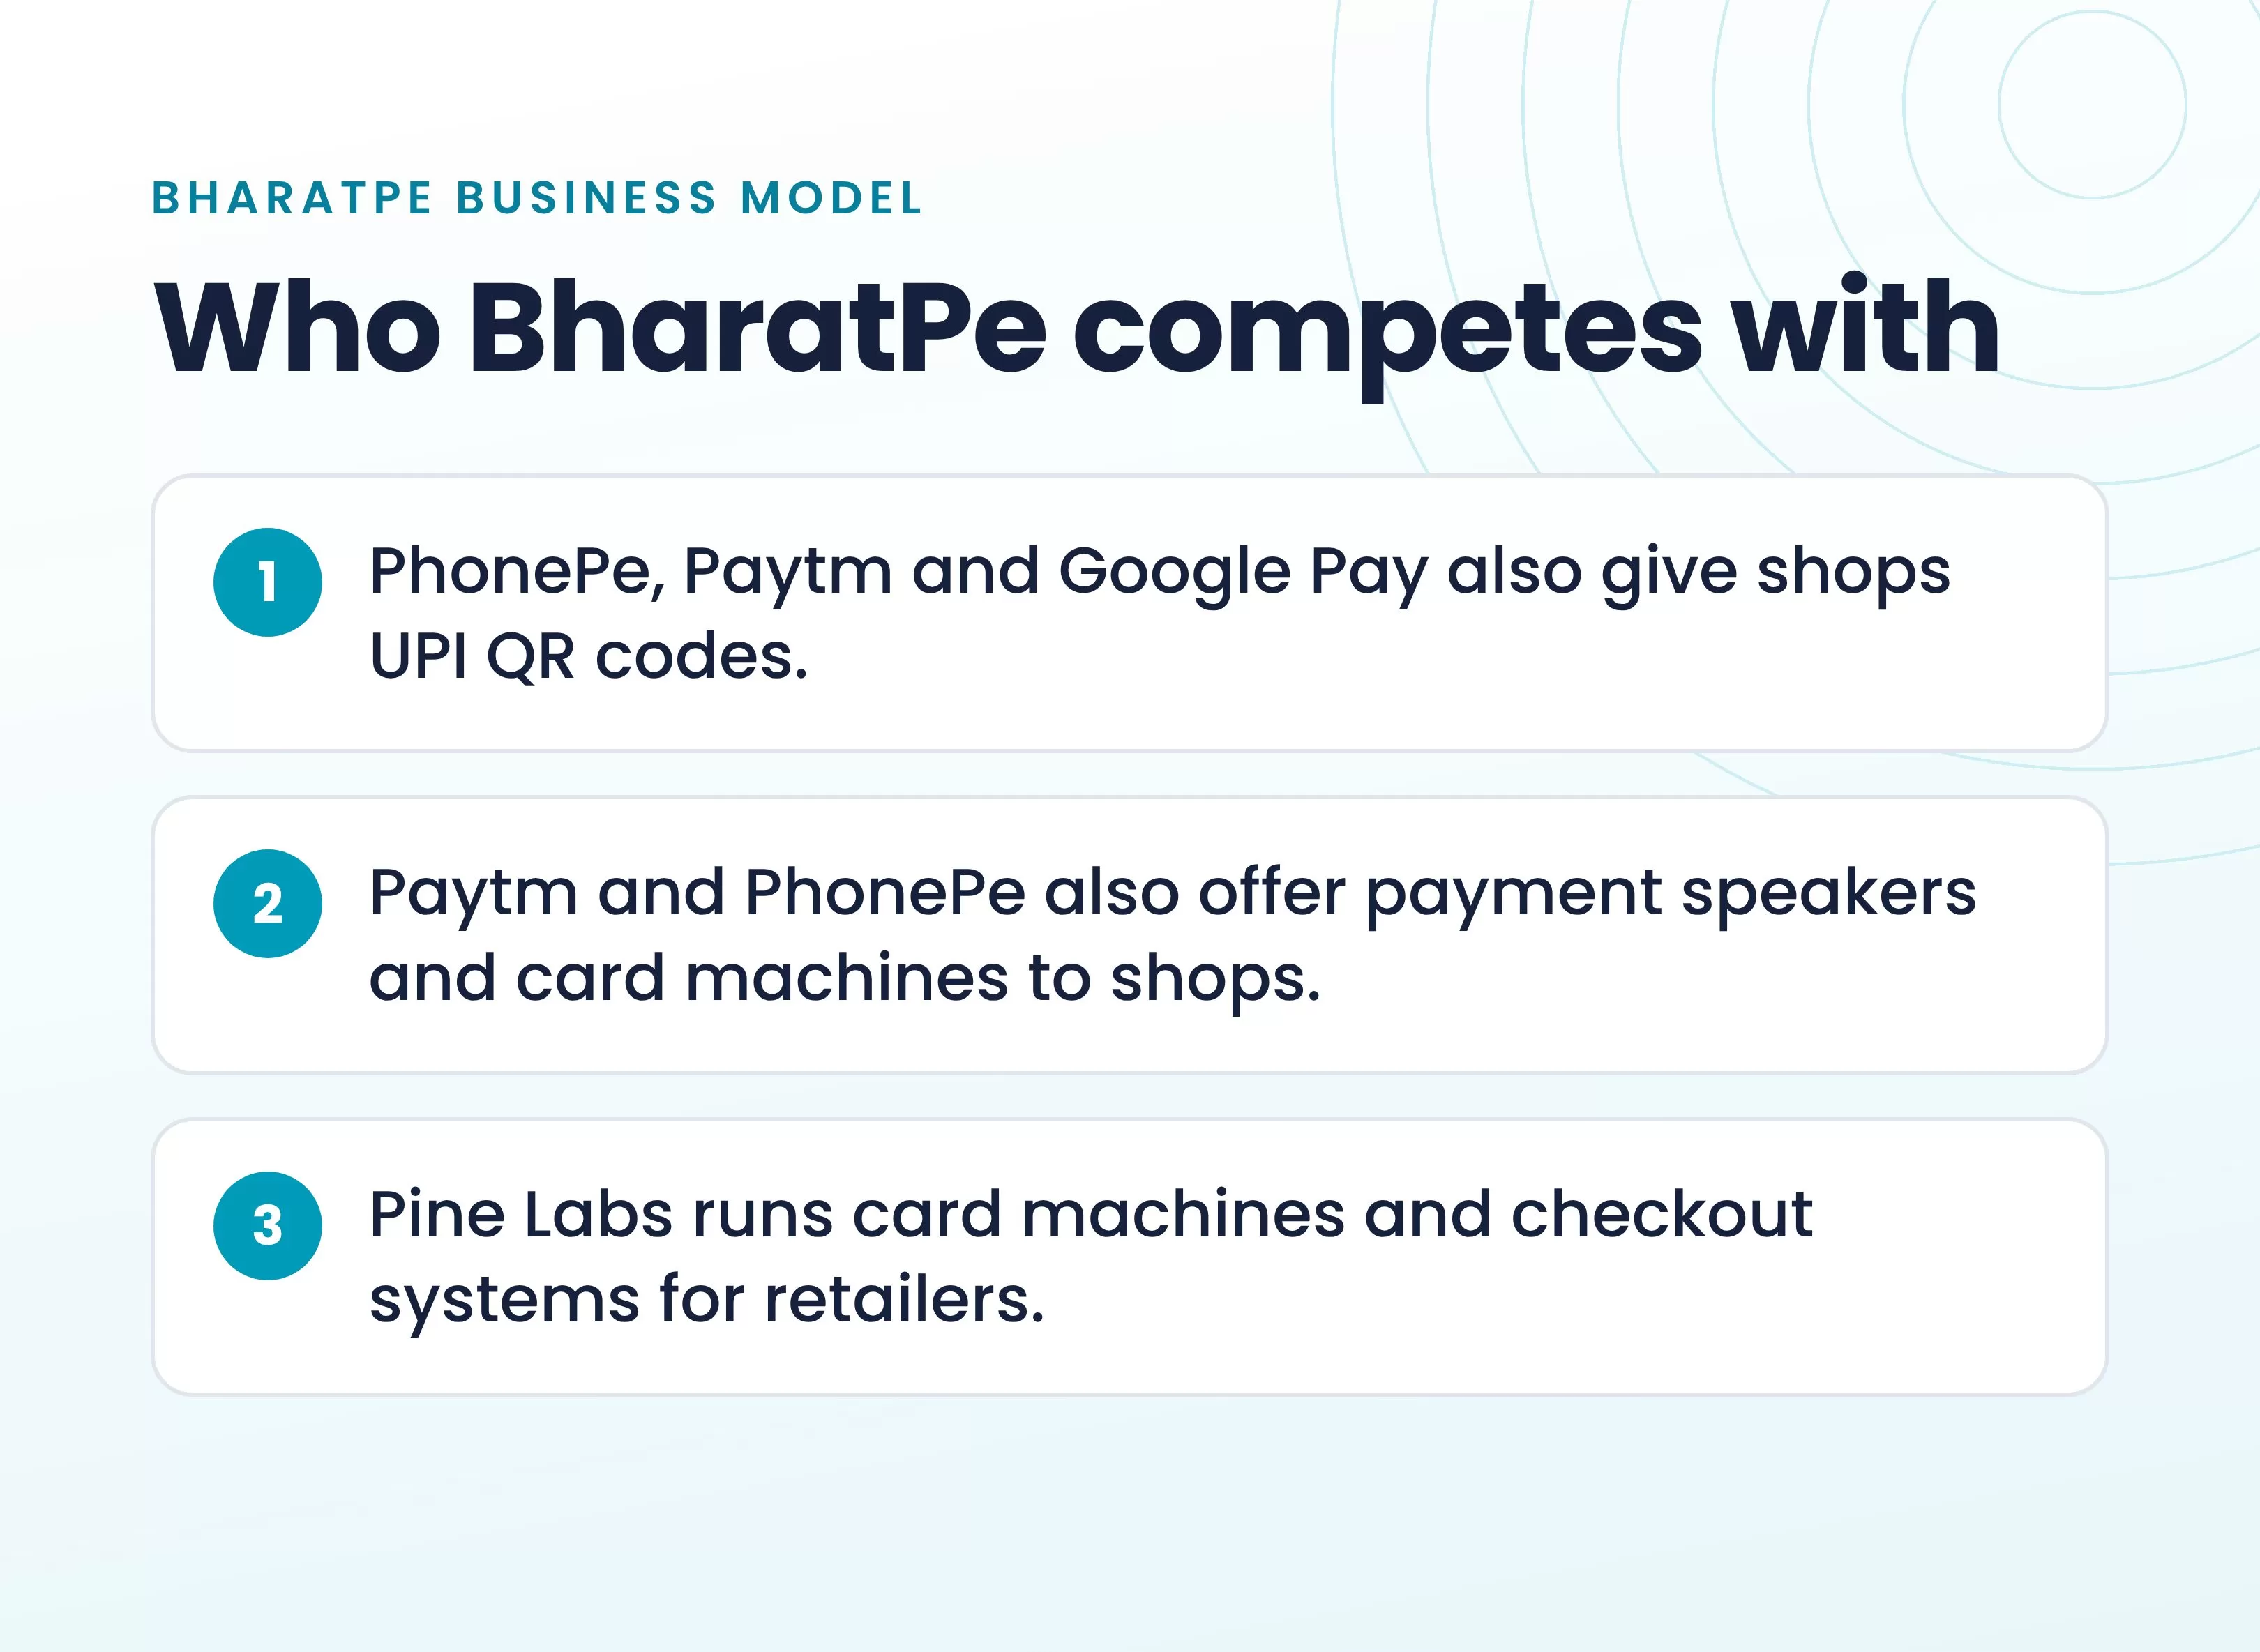
PhonePe, Paytm and Google Pay also give shops UPI QR codes. Paytm and PhonePe also offer payment speakers and card machines to merchants. Pine Labs runs card machines and checkout systems for retailers.
Challenges BharatPe faces
BharatPe reported a net loss of ₹88.2 crore in FY25, even though its adjusted profit before tax was positive. It holds a stake in Unity Small Finance Bank alongside Centrum, and the two are in a shareholder dispute before the Delhi High Court. The company is unlisted. CEO Nalin Negi said in August 2025 that it will list when market conditions are right, and no IPO date has been set.
Conclusion on the BharatPe business model
BharatPe gives shopkeepers QR codes, card machines and payment speakers, then uses their payment data to offer them loans through BharatPe Capital and partner lenders. In FY25, most of its revenue came from financial services, mainly merchant lending, and the rest from payments.
In FY25 it reported revenue from operations of ₹1,667 crore and a net loss of ₹88.2 crore.


